

Blogs
Magnetic Bead Purification Kits Market: Why 6.6% CAGR Reshapes the DNA/RNA Landscape
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Magnetic Bead Purification Kits Market
The magnetic bead purification kits market has evolved from a niche laboratory tool into a critical component of modern molecular diagnostics, pharmaceutical development, and genomic research. At its core, the market enables the isolation of nucleic acids and proteins with greater reproducibility, scalability, and compatibility with automation than traditional column-based methods. This shift is not merely technical; it reflects a broader transformation in how biological samples are processed across clinical, industrial, and academic settings. For decision-makers evaluating long-term positioning in life sciences reagents and consumables, understanding the trajectory of this market requires looking beyond product specifications to the structural forces shaping demand, competition, and innovation cycles.
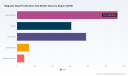
The global market for magnetic bead purification kits reached an estimated revenue base of 274.0 million in 2025, expanding from approximately 200.0 million in 2020. Growth over this period reflects sustained adoption across research and clinical workflows, with the market projected to advance at a compound annual growth rate of 6.6 percent through 2032, reaching roughly 426.49 million. The expansion is not evenly distributed across product types or end-use segments, but the overall trajectory signals a maturing market where differentiation, regulatory readiness, and workflow integration increasingly determine competitive advantage. Revenue concentration remains notable, with the top three players capturing around half of total market value and the top five holding approximately two-thirds, indicating that scale, brand trust, and established distribution channels still confer meaningful advantages. At the same time, the presence of specialized and regionally strong suppliers suggests that targeted product strategies and application-specific solutions continue to carve out defensible positions.
PW Consulting
Several structural challenges and inflection points define the current environment. First, the market is navigating a transition from broadly applicable research kits toward application-specific, regulatory-compliant solutions for clinical diagnostics and high-throughput testing. Kits that perform reliably in a research laboratory do not automatically meet the reproducibility, traceability, and clearance requirements demanded in molecular diagnostic workflows. This creates a divide between suppliers that have invested in validation, documentation, and regulatory pathways and those that remain primarily focused on research-grade offerings. Second, supply chain sensitivity around high-purity magnetic beads and specialized buffers has become a practical constraint. The performance of purification kits depends heavily on bead chemistry, surface functionalization, and buffer composition, meaning that shortages, quality inconsistencies, or cost volatility in critical inputs can disrupt both product development and customer trust. Third, the rising importance of automated platforms is reshaping purchasing logic. Laboratories and clinical operations increasingly view purification kits not as standalone consumables but as part of integrated workflows that include instrumentation, software, and throughput requirements. Suppliers that cannot align their kits with automated systems risk being bypassed in favor of more compatible solutions, even if their chemistry is competitive on a standalone basis.
The market’s expansion is being propelled by a combination of technological, regulatory, and demand-side forces that reinforce one another. Technological innovation remains the most visible driver. Magnetic bead chemistry continues to advance in ways that directly affect throughput, purity, and applicability to demanding downstream applications. High-molecular-weight DNA extraction, viral nucleic acid purification, and circulating free DNA isolation are examples where bead design and buffer systems determine whether a kit can support long-read sequencing, sensitive diagnostics, or reproducible biomarker workflows. Recent product introductions illustrate this trajectory. The launch of magnetic bead kits optimized for high-molecular-weight DNA extraction and automated workflows reflects a clear alignment between chemistry and the needs of long-read sequencing platforms, where fragment integrity and consistent yield are essential. Similarly, magnetic bead solutions designed for high-throughput viral nucleic acid purification from saliva, respiratory swabs, and wastewater demonstrate how purification kits are increasingly tailored to sample types and testing scenarios rather than generic isolation tasks. These developments matter commercially because they expand the addressable use cases for magnetic bead kits beyond conventional research workflows and into settings where performance specifications are tightly linked to downstream value.
Regulatory and policy environments are shaping the market with increasing force. For clinical applications, magnetic bead-based kits intended for viral and circulating free DNA purification increasingly require in vitro diagnostic clearance, CE marking, or regulatory submissions that document performance and safety. This does not simply add compliance costs; it changes the market’s structure by raising barriers for new entrants and rewarding established suppliers with regulatory experience, quality systems, and validated manufacturing processes. At the same time, regulatory expectations are also influencing product design in subtler ways. Features such as thermal stability, compatibility with sterilization procedures, and consistent lot-to-lot performance are becoming more important as laboratories seek to reduce contamination risk and maintain dependable results across high-volume workflows. Supplier claims around easy autoclave sterilization and thermal stability, for example, are not just technical specifications; they address operational concerns that matter in regulated or high-throughput environments. The practical effect is that regulatory dynamics are pushing the market toward more standardized, validated, and workflow-ready solutions, which favors companies that can provide both the chemistry and the evidentiary support needed for clinical adoption.
Demand-side behavior is also changing the market’s direction. Molecular diagnostics and infectious disease testing continue to drive usage of nucleic acid extraction workflows across clinical laboratories, creating steady demand for purification kits that can be deployed in routine testing and surge scenarios alike. This is not solely a function of outbreak response; it reflects the broader integration of molecular testing into standard diagnostic pathways. Academic and research institutions remain significant users, but the nature of demand is shifting as laboratories prioritize reproducibility, scalability, and compatibility with automated processing. Pharmaceutical and biotechnology companies increasingly rely on purification kits as part of complex development workflows, where consistency and documentation can influence decision-making from early discovery through clinical-stage work. The commercial implication is that demand is becoming more segmented by performance requirements and less driven by price alone. Buyers in diagnostic and industrial settings are often willing to accept premium pricing if a kit reduces variability, integrates with existing instruments, or supports regulatory documentation, while research buyers may remain more price-sensitive but increasingly value workflow efficiency and technical support.
Cost and supply chain structures are influencing competitive positioning in ways that merit close attention. Magnetic bead purification kits depend on specialized raw materials and precise manufacturing controls, which means that material costs, quality assurance, and supply resilience all affect margin stability and customer reliability. High-purity beads and purpose-built buffers are essential for consistent performance in applications such as viral RNA and circulating free DNA isolation, so any disruption in sourcing or production can have outsized consequences. Over time, this dynamic encourages consolidation among suppliers that can secure reliable input streams, standardize manufacturing, and invest in quality systems. It also creates opportunities for companies that can differentiate through manufacturing efficiency, regional supply agility, or kit designs that reduce waste and handling complexity. The broader point is that the market is increasingly rewarding operational excellence as much as product innovation, because performance claims are only valuable if they can be delivered consistently at scale.
The competitive landscape is characterized by a mix of large, diversified life sciences companies and specialized suppliers with strong application focus. Thermo Fisher Scientific maintains a prominent position through magnetic bead-based nucleic acid purification kits and automated extraction workflows, with product lines that emphasize compatibility with high-throughput processing and a range of sample types. Its recent emphasis on high-molecular-weight DNA kits and automated workflow optimization illustrates a strategy centered on aligning chemistry with instrumentation and downstream applications. Qiagen contributes a broad portfolio of magnetic bead kits for nucleic acid and protein purification, including solutions for viral RNA and circulating free DNA isolation. Its positioning reflects deep experience in sample preparation and a focus on validated workflows that can bridge research and diagnostic use. New England Biolabs has strengthened its presence through magnetic bead-based kits designed for high-throughput viral nucleic acid purification, a move that highlights the importance of sample-type specificity and workflow throughput in contemporary product strategy.
Worldwide AAV Purification Kit Market
PerkinElmer’s acquisition of Covaris illustrates a broader consolidation trend in which companies expand their capabilities by combining chemistry, instrumentation, and sample preparation technologies. The integration of magnetic bead-based extraction kits with automated platforms creates a more complete value proposition for customers seeking streamlined workflows, and it signals that competitive advantage increasingly depends on how well a supplier can connect consumables with equipment and software environments. Promega and Revvity both emphasize magnetic bead-based purification across research and diagnostic workflows, with Revvity’s technology highlighting multi-sample-type compatibility and automation readiness. These strategies reflect a shared industry direction: suppliers are seeking to reduce friction for customers by offering kits that work across platforms, sample types, and throughput requirements. Smaller and regionally focused companies such as Norgen Biotek, Bioneer, TIANGEN Biotech, Zymo Research, Geneaid, Omega Bio-tek, RayBiotech, Diagenode, Magbio Genomics, and others remain important participants by serving specialized needs, regional markets, or application niches. Their continued presence suggests that the market is not simply consolidating into a few dominant players; rather, it is stratifying into broad-platform leaders and focused specialists, each competing on different dimensions of performance, support, and accessibility.
The strategic positioning of leading companies reveals several recurring advantages. Scale and brand trust help secure adoption in regulated and high-volume settings, where switching costs and validation burden favor established suppliers. Broad product portfolios and automation compatibility broaden the addressable market and create cross-selling opportunities across kits, instruments, and service offerings. At the same time, differentiated chemistry and application-specific validation allow smaller or focused companies to compete where performance requirements are exacting or where regional support and responsiveness matter. Recent industry moves support this interpretation. Product launches that target high-molecular-weight DNA extraction, viral nucleic acid purification, and compatibility with automated particle processors show how suppliers are aligning their roadmaps with the practical needs of laboratories and diagnostic operations. Acquisitions and platform integrations further suggest that the market is moving toward bundled solutions in which purification kits are evaluated as part of a larger workflow rather than as isolated reagents. The competitive trend, then, is not simply toward larger players but toward more integrated, workflow-aware offerings that reduce operational complexity for end users.
Looking ahead, the market is likely to be shaped by a few interconnected trends over the next several years. One is the continued shift toward automation-compatible, workflow-integrated kits. As laboratories and clinical operations expand high-throughput processing, suppliers that can ensure their kits work seamlessly with common magnetic particle processors and automated extraction systems will capture a growing share of demand. This trend creates commercial opportunities for companies that design kits with automation in mind from the outset, including consistent handling characteristics, compatibility with standard instrumentation, and packaging or format choices that reduce manual intervention. It also raises the stakes for suppliers whose kits are difficult to automate or require extensive protocol adjustment. A second trend is the deepening alignment between purification kits and diagnostic regulation. As molecular testing becomes more embedded in routine clinical workflows, the importance of cleared or certifiable solutions will increase. Products that can support viral and circulating free DNA purification under appropriate regulatory frameworks are likely to benefit from stronger demand in diagnostic settings, while also facing higher development and compliance costs. This trend opens opportunities for suppliers that can provide documentation, validation support, and regulatory readiness, but it also introduces uncertainty for those that rely primarily on research-grade positioning and may face pressure to adapt if clinical adoption expands faster than expected. A third trend is the growing importance of specialized applications such as high-molecular-weight DNA, viral pathogen detection, and circulating free DNA workflows. These areas are driven by sequencing technology advancement, infectious disease testing, and liquid biopsy–related research, all of which place distinct demands on purification performance. The commercial opportunity lies in designing kits that meet the specific yield, purity, and integrity requirements of these applications while also supporting scalable processing.
Magnetic Beads Market
These trends carry both opportunity and risk. The upside is clear: workflow integration, regulatory-aligned products, and application-specific chemistry can expand margins and strengthen customer loyalty in high-value segments. The risks are equally important. Overinvestment in highly specialized kits without sufficient demand depth can leave suppliers exposed if downstream applications shift. Regulatory timelines and requirements can vary across markets, complicating global launches and creating uneven growth. Supply chain fragility for critical inputs can undermine performance claims and reduce trust if quality issues arise. In addition, automation adoption is not uniform; some laboratories continue to rely on manual or semi-automated processes, meaning that the pace of transition to fully integrated workflows may vary by region, institution type, and application. Decision-makers should therefore weigh both the direction of change and the unevenness with which it will be adopted.
For manufacturers, the strategic priority is to build differentiation that survives beyond product specifications. That means aligning chemistry, workflow compatibility, and documentation so that customers can adopt kits with confidence in both research and clinical contexts. Companies should evaluate whether their portfolios are sufficiently connected to automation platforms and whether they can support customers through validation, training, and stable supply. Where specialization is pursued, it should be tied to applications with credible demand depth and clear performance requirements, rather than to incremental variations that do not change customer outcomes. For investors, the market offers interest in companies that combine defensible chemistry with strong workflow integration, regulatory readiness, and reliable manufacturing. Attention should be paid to suppliers that are expanding platform compatibility, improving margin stability through supply chain control, or positioning themselves in higher-value diagnostic and biopharmaceutical workflows. At the same time, investment theses should account for regulatory exposure, input cost sensitivity, and the possibility that automation adoption will reshape the relative attractiveness of manual versus automated kit formats. For procurement and laboratory operations, the emphasis should be on total workflow value rather than unit price alone. This includes assessing how well a kit integrates with existing instrumentation, how consistently it performs across sample types, and whether the supplier can support regulatory or quality documentation when needed. Building relationships with suppliers that can scale with throughput requirements and reduce operational variability is likely to pay off as testing and research workloads become more complex.
The commercial picture that emerges is one of steady growth underpinned by real shifts in how nucleic acid and protein purification are performed across research, clinical, and industrial settings. The market is large enough to reward scale, but it is also segmented enough to reward focus. Successful players will be those that can couple reliable chemistry with automation compatibility, regulatory alignment, and the operational resilience needed to deliver consistent results at volume. For organizations seeking to navigate this landscape with greater precision, detailed segmentation, regional dynamics, and company-specific benchmarking can sharpen strategy further. A comprehensive research report on the Magnetic Bead Purification Kits Market can provide the deeper data and customized analysis needed to translate these strategic trends into concrete decisions.
For detailed analysis of this topic, please visit the official page: Magnetic Bead Purification Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Conference System Market: How Wireless Shift and 7.6% CAGR Reshape Growth
By PW Consulting, 2026-09-21
The Conference System (Microphone) Market: Strategic Trends and Commercial Opportunities Through 2032
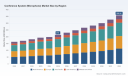
The conference system microphone market is entering a period of structural expansion, moving beyond incremental improvements in audio fidelity toward comprehensive integration of digital infrastructure, hybrid meeting capabilities, and intelligent audio processing. With total market revenue projected to grow from approximately 215.0 million USD in 2025 to 358.54 million USD by 2032, the sector is tracking a compound annual growth rate of 7.62 percent across the 2026–2032 forecast window. This trajectory reflects a fundamental shift in how organizations conceptualize meeting spaces: audio capture is no longer a peripheral accessory but a central component of collaboration infrastructure, governance workflows, and enterprise productivity ecosystems.
Historical revenue progression from 2020 through 2025 illustrates steady acceleration, with the market expanding from 163.15 million USD to 215.0 million USD. The post-pandemic normalization of hybrid work patterns, coupled with sustained capital expenditure in corporate real estate modernization and public sector digital transformation initiatives, has created a durable demand baseline. Yet the market’s growth narrative is not simply a function of volume expansion. It is increasingly defined by technology substitution, infrastructure readiness, regulatory alignment, and competitive repositioning among manufacturers that must balance performance differentiation with supply chain economics.
Market Landscape and Core Challenges
The conference microphone market operates at the intersection of professional audio engineering, networked IT infrastructure, and organizational behavior. Revenue expansion is being driven by installations that treat microphone arrays, discussion units, and ceiling-mounted capture systems as integral components of unified meeting environments. However, several structural challenges are shaping how manufacturers, integrators, and end users navigate the next phase of market development.
Infrastructure Alignment and Installation Complexity
Networked conference systems increasingly depend on robust cabling standards and centralized audio processing architectures. Ethernet infrastructure upgrades for simultaneous interpretation in large assembly spaces require Cat 6A cabling to maintain signal integrity and latency thresholds. This infrastructure dependency creates a practical bottleneck: facilities that upgrade meeting rooms often discover that audio hardware deployment cannot outpace network modernization. For manufacturers and solution providers, this means product roadmaps must account for installation environments that vary widely in readiness, from greenfield corporate campuses to retrofitted legacy government buildings.
Cost Structures and Component Sensitivity
Wireless conference microphone designs face material cost pressures that influence pricing strategy and margin management. Polymer housings and rare-earth magnets in wireless conference microphones contribute approximately 18 percent to total unit cost in 2026 supply chains. This cost composition matters because it ties product economics to commodity markets and manufacturing geography. Companies that rely heavily on wireless form factors must navigate input cost volatility while still delivering the mobility and deployment flexibility that enterprise buyers increasingly expect. The result is a market where supply chain optimization is becoming as strategically relevant as acoustic performance.
Regulatory Compliance and Procurement Pathways
Standardization and public procurement dynamics are shaping market access. Digital infrared conference systems must comply with IEC 60914 for electromagnetic compatibility and safety in public meeting spaces. At the same time, conference microphone systems in government facilities are eligible for public procurement funding under digital government modernization programs. These two forces create a dual dynamic: compliance requirements raise the barrier for entrants that cannot meet certification expectations, while modernization funding expands the addressable base in public sector settings. Manufacturers that align product certification and procurement positioning with these frameworks gain a structural advantage in segments where purchasing decisions are less price-sensitive and more specification-driven.
Key Demand Drivers
The market’s expansion is being propelled by a combination of technological, regulatory, behavioral, and supply-side developments. Each driver reinforces the others, creating a landscape where audio capture is becoming more networked, more automated, and more tightly integrated with broader collaboration workflows.
Technology Innovation and Intelligent Audio Processing
One of the most significant shifts is the move from standalone microphone hardware toward integrated audio processing chains. Ceiling and table array microphones, wireless discussion systems, and all-in-one audio bars are increasingly paired with digital signal processing that handles noise suppression, beamforming, automatic mixing, and speaker tracking. This evolution reduces the burden on end users to tune audio environments manually and supports consistent capture quality across varied room configurations. The practical implication is that manufacturers are competing not only on microphone sensitivity or form factor, but on the intelligence embedded in the acoustic pipeline. Companies that can deliver predictable audio performance across hybrid and in-room scenarios are gaining traction with IT and facilities teams that need to manage many meeting spaces without specialized audio engineering support.
Hybrid Meeting Behavior and Coverage Demand
Hybrid meeting adoption has increased demand for wireless conference microphone coverage by 45 percent in enterprise environments since 2024. This behavioral shift reflects a durable change in how organizations operate: meetings are no longer confined to a single room with all participants present. Instead, distributed participation has become routine, and audio capture must serve both in-room clarity and remote intelligibility. Wireless coverage expansion is not simply about adding more devices; it is about ensuring that discussion systems can accommodate mobile participants, flexible seating arrangements, and multi-site integration. For solution providers, this means product portfolios must support rapid redeployment, simplified pairing, and seamless integration with video and collaboration platforms. The enterprise buyer is increasingly evaluating microphones not as isolated audio tools, but as components of a broader hybrid collaboration architecture.
Public Sector Modernization and Formal Gathering Requirements
Government facilities, legislative bodies, and large institutional meeting spaces continue to represent a meaningful demand base for formal conference systems. Digital wired and wireless conference systems, paperless solutions, and hybrid meeting technologies for formal gatherings are particularly relevant where voting, simultaneous interpretation, and recorded proceedings are part of the operational workflow. Public procurement funding tied to digital government modernization programs further supports adoption in these environments. At the same time, compliance expectations around electromagnetic compatibility and safety reinforce the importance of certified, proven systems. This segment rewards manufacturers that can offer durable, specification-aligned solutions with clear support for formal meeting processes rather than purely casual collaboration use cases.
Supply Chain and Cost Architecture Realignment
Beyond component cost sensitivity, the broader supply chain environment is influencing product strategy. Manufacturers are reassessing how much functionality is integrated into a single device versus distributed across networked endpoints. Ethernet-based networked conference systems introduce different cost and deployment considerations compared with standalone infrared or wired discussion units. Meanwhile, raw material exposure in wireless designs encourages engineering teams to explore material efficiency, modular architecture, and manufacturing footprints that can better absorb input cost fluctuations. The practical outcome is a market in which product differentiation is increasingly tied to total cost of deployment rather than unit price alone. Buyers are weighing installation labor, cabling requirements, management overhead, and long-term maintainability alongside acoustic specifications.
Competitive Positioning and Strategic Evolution
The competitive landscape is shaped by manufacturers that have built reputations across professional audio, conference systems, and integrated meeting solutions. The market remains moderately fragmented, with concentration levels indicating room for both specialization and consolidation. This environment rewards companies that can combine product reliability, deployment practicality, and clear alignment with the use cases their customers prioritize.
Differentiation Through Integrated System Design
Several established players have emphasized end-to-end discussion and audio processing ecosystems rather than isolated microphone products. For example, some manufacturers focus on ceiling and table array microphones paired with advanced audio processing for hybrid conference rooms, creating a compelling value proposition for organizations that want consistent capture without complex tuning. Others prioritize digital wired and wireless conference systems with main units and multimedia devices designed for structured meetings, which appeals to customers with formal deliberation, voting, or interpretation requirements. There are also vendors emphasizing all-in-one meeting audio solutions and ceiling microphone arrays that simplify installation in modern collaboration spaces. These approaches illustrate a broader competitive theme: differentiation is increasingly defined by how well a product portfolio addresses the full meeting workflow, from audio capture to processing to integration with room systems.
Worldwide Pro Microphone Market
Regional and Segmental Specialization
Competitive positioning also varies by market orientation. Some manufacturers have strong presence in enterprise collaboration environments where wireless flexibility and hybrid coverage are priorities. Others have built credibility in formal government and institutional settings where wired and infrared systems, certification compliance, and paperless meeting capabilities are central. Asian manufacturers, in particular, have expanded digital conference system offerings with wireless and paperless multimedia solutions, reflecting both scaling capacity and growing emphasis on feature parity with established Western brands. This diversification means that procurement teams often evaluate suppliers not just by brand familiarity, but by how well a vendor’s portfolio matches the operational profile of the facility and the expectations of the meeting participants.
Market Evolution Toward Consolidation and Capability Concentration
The market is likely to see continued pressure toward consolidation among companies that can combine audio hardware, DSP software, and integration support under a coherent portfolio. At the same time, specialized entrants may thrive by targeting narrow requirements such as ceiling array optimization, wireless discussion scalability, or AI-enhanced capture for specific room types. Recent trade show activity underscores this dynamic. VISSONIC exhibited a full line of digital conference systems, ceiling microphones, and paperless multimedia units at ISE 2026 in Barcelona. TAIDEN launched and showcased a fully digital conference main unit, a conference flex dock, and paperless multimedia terminals at the same event, and later presented additional conference solutions at InfoComm China 2026. These moves highlight how manufacturers are using major industry events to reinforce product breadth, demonstrate integration readiness, and signal momentum in both wired and wireless conference categories.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2032 period, the market’s trajectory will be shaped by the interaction of technology maturity, facility readiness, and purchasing behavior across enterprise, education, public sector, and large-event environments. Three trends appear especially consequential.
Trend One: From Device Sales to Managed Audio Environments
Meeting audio is increasingly treated as an environment to be managed rather than a device to be purchased. This shift favors solutions that can be centrally configured, monitored, and updated across multiple rooms. Manufacturers and integrators that offer repeatable deployment templates, remote diagnostics, and consistent processing performance will be better positioned to capture multi-site contracts. The commercial opportunity lies in building offerings that reduce operational friction for IT and facilities teams, because those teams are often the real gatekeepers in scaled rollouts.
Trend Two: Wireless Expansion Balanced by Infrastructure and Cost Realities
Wireless microphone coverage demand will continue to grow, especially in enterprise settings where hybrid participation is standard. However, growth will be moderated by cabling constraints, electromagnetic compliance expectations, and material cost exposure in wireless units. The practical implication is that product strategies will need to balance mobility with reliability and total deployment cost. Manufacturers that can offer wireless flexibility without creating hidden installation or maintenance burdens will gain a competitive edge. This is also where supply chain discipline becomes commercially visible: pricing stability, predictable lead times, and component efficiency will matter as much as feature lists.
Trend Three: Formal and Public Sector Demand as a Stabilizing Anchor
Government modernization funding, formal meeting requirements, and compliance-driven procurement will continue to provide a stable demand base. This segment values certification, durability, and workflow support such as voting, interpretation, and paperless operations. The opportunity for manufacturers is to align product certification, documentation, and support models with public procurement expectations while also offering enough flexibility to serve hybrid and multimedia needs. In practice, this means that solutions designed for formal gatherings can benefit from clear differentiation on reliability and procedural support, rather than competing solely on cost.
Risks and Uncertainties
Several factors could temper the market’s growth path. If enterprise real estate investment slows, meeting room upgrades may be deferred, reducing near-term procurement velocity. If wireless component costs rise further, pricing pressure could compress margins or slow adoption in cost-sensitive segments. If compliance or infrastructure requirements become more stringent without corresponding procurement support, installation timelines could lengthen, particularly in large halls and public facilities. Finally, if hybrid meeting practices stabilize into a narrower set of use cases, the demand surge for expanded wireless coverage could moderate. These uncertainties do not negate growth, but they suggest that forecast confidence will depend on how well manufacturers and buyers manage deployment complexity and total cost.
Strategic Guidance for Decision Makers
The market’s expansion creates distinct implications depending on a decision maker’s role. While the following recommendations are general in nature, they highlight where attention is likely to yield the greatest strategic value.
PW Consulting
For Manufacturers and Solution Providers
- Align product roadmaps with total deployment cost, not just unit performance. Ethernet readiness, cabling requirements, and installation labor increasingly shape purchasing decisions, so designs that simplify integration can win even when acoustic specifications are comparable.
- Invest in intelligent audio processing and repeatable room templates. Consistent capture across varied environments reduces the operational burden on end users and strengthens multi-site sales opportunities.
- Manage supply chain exposure in wireless product lines. Given the material cost contribution of polymer housings and rare-earth magnets, manufacturers should evaluate component efficiency, sourcing resilience, and pricing strategies that protect margin without sacrificing mobility features.
For Investors and Corporate Strategists
- Focus on companies that can combine hardware, processing, and integration support into coherent offerings. The market appears to reward portfolios that reduce complexity for buyers rather than those that compete on narrow hardware specs alone.
- Watch public sector modernization and compliance-aligned product positioning as indicators of durable demand. Certification readiness and procurement alignment can create stickier relationships in government and institutional segments.
- Monitor competitive moves around wireless coverage, ceiling array solutions, and paperless meeting capabilities, since these areas reflect where manufacturers are placing bets on future meeting behavior.
For Procurement and Facilities Leaders
- Evaluate conference microphone systems as part of the broader room infrastructure, including network cabling, interpretation requirements, and ongoing management. Total cost and deployment feasibility often matter more than headline device features.
- Prioritize compliance and certification where formal meetings, public spaces, or large halls are involved. Aligning procurement with recognized standards can reduce project risk and support smoother approval processes.
- Consider hybrid meeting behavior explicitly when specifying wireless coverage. Deployment plans should account for flexible seating, multi-site participation, and the practicalities of redeploying devices across spaces.
Closing Perspective
The conference system microphone market is expanding against a backdrop of hybrid work normalization, digital infrastructure upgrades, and growing expectations for consistent audio capture across meeting environments. Growth through 2032 will be shaped not only by demand volume, but by how effectively manufacturers, integrators, and buyers navigate infrastructure dependencies, cost structures, compliance requirements, and the shift toward managed audio environments. Strategic advantage will increasingly belong to those who treat conference microphones as part of an integrated collaboration architecture rather than as isolated components.
Worldwide Audio Conference System Market
For decision makers seeking deeper segmentation detail, company-level comparisons, and customized scenario planning, the full PW Consulting research report provides more granular data and targeted recommendations across region, type, and application dimensions.
For detailed analysis of this topic, please visit the official page: Conference System (Microphone) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Optical Transceivers Market 2026: How 13.5% CAGR Reshapes Data Center Competition
By PW Consulting, 2026-09-21
The Optical Transceivers Market: Strategic Trends and Commercial Opportunities in a High-Speed Era
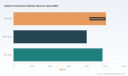
The global optical transceivers market has entered a phase of accelerated expansion, driven by an unprecedented surge in data traffic and the rapid deployment of high-performance computing infrastructure. From 2020 to 2025, the market experienced a compound annual growth rate that significantly outpaced broader semiconductor sectors, culminating in an estimated annual revenue of USD 13.9 billion for the base year 2025. This trajectory is projected to continue through the forecast period ending 2032, with the market size expected to more than double from its 2025 base. The sustained momentum suggests a CAGR of approximately 13.5 percent over the forecast horizon, indicating that optical connectivity is transitioning from a supporting component to a critical bottleneck and enabler of digital infrastructure.
However, this growth is not linear. The industry stands at a complex inflection point where technological capability, regulatory friction, and supply chain realities intersect. While demand signals from hyperscale data centers and telecommunications providers remain robust, the path to capturing value is fraught with challenges that require strategic navigation rather than passive participation. Understanding these dynamics is essential for executives and investors looking to position themselves advantageously in the coming cycle.
Market Landscape and Core Challenges
The current market environment is characterized by intense demand for higher bandwidth densities, yet this demand is mediated by significant structural constraints. The market size evolution from 2020 to 2032 reflects a compounding effect of data center expansion and network modernization, but the concentration of revenue among top players indicates a mature competitive field. With the top three and top five companies holding an identical market concentration share, the barrier to entry for new competitors remains high, while existing players must defend share through continuous innovation and cost efficiency.
Several key challenges define the current operational landscape. First, the transition to higher data rates such as 400G and 800G has introduced substantial complexity in manufacturing tolerances. Precision photonic components, including laser diodes and photodetectors, require stringent production controls. These technical requirements contribute to elevated unit costs, creating a cost structure that can strain margins if volume scaling does not materialize as expected. High manufacturing costs and component supply chain vulnerabilities result in elevated unit costs for 400G and 800G modules, making price sensitivity a relevant factor despite strong overall demand.
Worldwide Copper Transceivers Market
Second, geopolitical friction is reshaping supply chain strategies. US-China Technology Export Restrictions are disrupting supply chains for key optical components, forcing manufacturers to reconsider sourcing strategies and regional footprints. This regulatory environment introduces uncertainty regarding component availability and potential delays in product rollouts. Simultaneously, the EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, creating divergent regional incentives that complicate global standardization efforts.
Third, the industry must reconcile the pace of technological obsolescence with capital investment cycles. As hyperscale operators push for next-generation interconnects to support AI workloads, the window for profitable deployment of specific transceiver generations narrows. Companies must balance the risk of investing in standards that may evolve rapidly against the risk of falling behind in performance capabilities required by key customers. The industry must navigate the tension between performance leadership and manufacturing readiness, particularly as specifications move toward 1.6T and beyond.
Key Drivers of Market Evolution
The expansion of the optical transceivers market is underpinned by a convergence of technological, regulatory, and demand-side factors. Understanding the interplay between these drivers provides a clearer picture of where growth will originate and how value will be captured over the next several years.
Technological Innovation and Breakthroughs
The primary engine of growth remains the relentless push for higher data throughput per lane. The industry is shifting from 100G and 200G per lane architectures toward 400G and 800G standards, with early developments pointing toward 1.6T capabilities. This shift is not merely an incremental upgrade; it requires fundamental changes in transceiver design, including the adoption of advanced modulation formats, silicon photonics integration, and co-packaged optics.
Recent developments illustrate the pace of this innovation. In April 2025, Coherent Corp. demonstrated its 1.6T-SR8 optical transceiver based on advanced 200G VCSELs at OFC 2025. This demonstration highlights the industry's focus on pushing the limits of vertical-cavity surface-emitting laser technology to achieve higher densities without compromising power efficiency. Such advancements are critical for hyperscale AI data centers, where power and space constraints are as binding as bandwidth requirements.
Concurrently, the move toward co-packaged optics represents a structural shift in how optical interfaces are integrated with switching silicon. By moving the optical engine closer to the ASIC, vendors can reduce electrical interconnect losses and improve energy efficiency. Broadcom Inc. announced the shipment of its industry's first 102.4 Tbps co-packaged optics Ethernet switch with 200 Gbps per channel performance in October 2025. This milestone signals that co-packaged optics are moving from conceptual demonstrations to commercial shipments, opening new design paradigms for AI infrastructure. These technological breakthroughs directly influence market composition by creating demand for specialized transceiver modules and integrated optical engines that differ from traditional pluggable form factors.
Policy and Regulatory Environment
Regulatory frameworks are increasingly shaping market dynamics, influencing both supply chains and demand patterns. On one hand, trade restrictions and export controls are fragmenting the global supply base. The disruption of supply chains for key optical components creates divergence between regions that can access advanced manufacturing capabilities and those that face constraints. This environment incentivizes regionalization of production, as companies seek to mitigate risk by establishing local manufacturing hubs or securing supply from allied jurisdictions.
On the other hand, policy initiatives aimed at digital infrastructure development are stimulating demand. The EU's Push for Digital Sovereignty is stimulating local manufacturing and innovation in optical transceivers, while harmonized regulation under the European Electronic Communications Code is streamlining spectrum allocation and infrastructure deployment approvals. These regulatory improvements reduce friction for network operators deploying new capacity, indirectly boosting the addressable market for transceivers in European telecommunications and enterprise networks. Additionally, national strategies in Asia and North America continue to prioritize data center expansion and broadband connectivity, providing a stable policy backdrop for long-term infrastructure investment.
Demand-Side Dynamics
Demand for optical transceivers is driven by distinct but complementary applications. Data centers remain the largest application segment, fueled by the exponential growth of AI model training, cloud services, and content delivery networks. The concentration of revenue in this segment reflects the capital intensity of hyperscale facilities and their need for high-speed interconnects to manage massive datasets and distributed computing workloads.
Telecommunications networks form a significant secondary driver, as operators upgrade backbone and access networks to support 5G densification, fixed wireless access, and growing enterprise connectivity requirements. The need for coherent transceivers in long-haul and metro networks is sustained by the requirement to maximize capacity over existing fiber assets while preparing for future bandwidth demands. Enterprise networks also contribute to demand, particularly as organizations modernize LAN and WAN infrastructures to support hybrid work models, IoT deployments, and security requirements that demand higher throughput and lower latency.
Across all segments, the common thread is the expectation of sustained bandwidth growth. Users and enterprises are increasingly data-hungry, and applications such as high-definition video, real-time collaboration, and AI-driven services continue to push traffic volumes upward. This demand-side resilience provides a buffer against short-term cyclical fluctuations, ensuring that the underlying driver for optical connectivity remains strong.
Supply Chain and Cost Structure Changes
The supply chain for optical transceivers is undergoing structural adjustments in response to demand signals and geopolitical pressures. Manufacturers are investing in capacity expansion and geographic diversification to secure supply and reduce dependency on single-source regions. For example, Applied Optoelectronics, Inc. is expanding U.S. manufacturing capacity to meet high-volume demand for 800G and 1.6T datacom transceivers, reflecting a broader trend toward nearshoring or friend-shoring critical optical component production.
Cost structures are also evolving as technologies mature and volumes increase. While initial units for new generations like 1.6T carry premium pricing due to low yields and complex assembly, continued investment in automated manufacturing and photonic integration is expected to drive down per-bit costs over time. Companies that can achieve superior yield rates and scalable production processes will gain a competitive advantage in pricing power and margin retention. However, the need for stringent manufacturing tolerances and high-quality precision photonic components means that cost reduction cannot come at the expense of performance reliability, creating a narrow operational window for suppliers.
Competitive Landscape and Leading Strategies
The competitive environment in the optical transceivers market is defined by a mix of established multinational players, specialized optical component manufacturers, and region-specific challengers. Market concentration remains high, indicating that scale, technological leadership, and ecosystem relationships are critical determinants of success. Companies are pursuing differentiated strategies to capture value across various segments of the market.
Strategic Positioning of Key Players
Several companies illustrate the range of strategic approaches currently in play. Coherent Corp. has focused on vertically integrated silicon photonics, VCSEL arrays, and coherent transceivers, including 1.6T-DR8 modules for hyperscale AI data centers and enterprise interconnects. Their strategy emphasizes deep technological integration and the ability to deliver high-performance solutions that address the specific needs of AI-driven workloads. By demonstrating advanced 200G VCSEL-based transceivers, Coherent is positioning itself at the forefront of next-generation lane speeds.
Broadcom Inc. is pursuing a co-packaged optics platform strategy, developing optical I/O engines for AI infrastructure with direct chip-to-chip integration. Their announcement of a 102.4 Tbps co-packaged optics Ethernet switch underscores a commitment to rearchitecting the interconnect layer for future AI clusters. This approach targets the highest end of the market where performance and energy efficiency are paramount, potentially reshaping the form factor and integration model of optical transceivers over time.
Cisco Systems, Inc. continues to leverage its comprehensive portfolio of pluggable transceivers supporting 100G to 800G+ Ethernet in data center and metro networks. The acquisition of CoreOptics in March 2025 expanded its optical networking engineering teams in Europe and Asia, signaling a strategy of strengthening internal capabilities and geographic reach. Cisco's approach relies on breadth of product offerings and strong customer relationships across enterprise and service provider segments.
Lumentum Holdings Inc. focuses on 800G and 1.6T OSFP and coherent transceivers with hybrid photonic integrated circuits for data center interconnects. Their emphasis on hybrid integration reflects an effort to combine the benefits of different photonic technologies to achieve performance and manufacturability goals. Meanwhile, Accelink Technology Co., Ltd. and Eoptolink Technology Inc. are emerging as significant forces in the Asia-Pacific region, offering 800G and 1.6T silicon photonics OSFP transceivers and active optical cables for AI and data center networks. Their growth highlights the increasing capability and competitiveness of regional manufacturers.
Huawei Technologies Co., Ltd. offers the StarryLink series of 400G and 800G pluggable optical modules for intelligent computing and data center interconnect scenarios. Their strategy is closely tied to the broader ecosystem of intelligent computing platforms, which can provide integrated solutions for customers building large-scale compute clusters. Sumitomo Electric Industries, Ltd. emphasizes low-power, compact designs for optical transceiver modules, targeting applications where energy efficiency and form factor are critical constraints.
High Speed Optical Transceiver Market
Other notable players include Source Photonics, Inc., which provides 200G-per-lane 1.6T and 800G PAM4 transceiver families for telecommunications and data connectivity, and Infinera Corporation, known for intelligent coherent pluggable transceivers in the ICE series for long-haul and metro optical networks. NeoPhotonics Corporation focuses on photonic integrated circuit-based transceivers for high-performance networking applications. These companies illustrate the diversity of technological approaches and application focuses within the market. Credo Technology Group Holding Ltd entered the space with its ZeroFlap optical transceiver line in November 2025, delivering secure high-speed connectivity for 400G, 800G, and 1.6T network speeds, indicating that security features are becoming a differentiator in certain segments. Jabil Inc. launched 1.6T transceivers in April 2025 for AI/ML, HPC, and high-speed data center interconnects, demonstrating that large-scale manufacturing services firms are also entering the market with high-speed solutions.
Evolving Market Dynamics
The competitive landscape is likely to evolve along several axes. First, consolidation may continue as larger players acquire specialized technologies or talent to fill gaps in their portfolios, as seen with Cisco's acquisition of CoreOptics. Such moves can accelerate capability development but also intensify competition for key intellectual property and engineering resources.
Second, the market may see divergence between highly integrated solutions for AI hyperscale customers and more standardized pluggable modules for broader enterprise and telecom use. Companies that can serve both ends of the spectrum or choose a focused niche will need to align their R&D and manufacturing strategies accordingly. The rise of co-packaged optics and chip-to-chip integration suggests that the boundary between transceivers and switching silicon may blur, creating opportunities for players with expertise in both optical and electronic integration.
Third, regional dynamics will play an increasing role. Manufacturers in China are expanding their capabilities in high-speed silicon photonics and transceiver modules, potentially capturing significant share in regional data center and telecom markets. At the same time, regulatory pressures and the push for local manufacturing in regions like Europe and North America may lead to a more fragmented supply base, with local content requirements influencing procurement decisions. Companies that can navigate these regional nuances while maintaining global quality and performance standards will be better positioned to scale.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to shape the optical transceivers market and create distinct commercial opportunities. Anticipating these trends allows decision-makers to align investments, product roadmaps, and partnership strategies with the direction of market evolution.
Acceleration of High-Speed Lane Rates and Form Factor Evolution
The transition toward 1.6T and potentially higher lane rates will accelerate as AI workloads continue to demand greater interconnect bandwidth. This trend will drive demand for transceiver modules that can support 200G per lane and beyond, while also pushing the industry to develop new form factors that balance density, power, and thermal management. Commercial opportunities lie in developing transceivers that offer superior energy efficiency per bit, as power consumption becomes an increasingly critical constraint in dense data center environments. Vendors that can demonstrate meaningful improvements in watts per gigabit will find strong demand from hyperscale operators seeking to manage total cost of ownership.
Additionally, the proliferation of co-packaged optics may create opportunities for suppliers of optical engines and integrated photonic modules that differ from traditional pluggable formats. Companies that can deliver reliable, scalable co-packaged solutions with strong integration support will be well-positioned to participate in next-generation switch architectures. However, this transition also introduces risk, as the adoption rate of co-packaged optics may vary across customer segments, and standards maturity could influence deployment timelines.
Regionalization and Supply Chain Resilience
The trend toward regionalization of manufacturing and supply chains is expected to continue, driven by both regulatory pressures and customer preferences for resilient sourcing. This creates opportunities for manufacturers that invest in local production capabilities or secure partnerships within target regions. Companies that can offer transparency, flexibility, and compliance with regional content requirements may gain preferential access to key accounts in government, telecommunications, and enterprise sectors. Conversely, suppliers heavily reliant on single-geography supply chains may face increasing challenges in serving global markets, necessitating strategic adjustments in sourcing, distribution, and partnerships.
For investors, this trend suggests that companies with diversified manufacturing footprints or strong alignment with regional digital infrastructure initiatives may offer more resilient growth profiles. The ability to navigate export controls and trade restrictions while maintaining product availability will be a valuable competitive attribute. Companies that can demonstrate robust supply chain management and compliance frameworks will differentiate themselves in an environment where geopolitical risk is a material consideration.
Integration of Advanced Features: Security, Intelligence, and Modulation Flexibility
As networks become more complex and security requirements intensify, transceivers that incorporate advanced features beyond raw bandwidth will gain relevance. The launch of secure high-speed connectivity solutions indicates that authentication, encryption, and tamper resistance are emerging as value-added attributes for certain customer segments. Commercial opportunities exist for vendors that can embed security features without significant penalties in power, cost, or performance. Similarly, transceivers with flexible modulation capabilities or software-defined configurations may appeal to operators seeking to optimize network resources dynamically across different traffic patterns and service requirements.
Intelligent transceivers that provide telemetry, diagnostics, and proactive maintenance capabilities may also find demand in large-scale networks where operational efficiency is paramount. The ability to monitor performance parameters in real time and predict failures can reduce downtime and optimize capacity planning, creating value for network operators managing diverse infrastructure. Vendors that integrate these capabilities into their product offerings can differentiate beyond price and performance specifications.
Potential Risks and Uncertainties
Despite the positive growth outlook, several risks warrant attention. The pace of adoption for next-generation standards such as 1.6T may be influenced by the readiness of host devices, switch ecosystems, and fiber plant capabilities. If the broader infrastructure does not evolve in lockstep, demand for ultra-high-speed transceivers could be delayed or concentrated in a narrower set of applications. Additionally, macroeconomic conditions affecting capital expenditure cycles could alter the timing of deployments, particularly in enterprise and telecom segments that are more sensitive to budget constraints than hyperscale data centers.
Technological risk remains significant, as rapid innovation can render current product generations obsolete faster than anticipated. Companies must balance the cost of R&D and capacity investment against the uncertainty of standards evolution and customer adoption. Overinvestment in a specific technology path that loses out to an alternative approach could lead to stranded assets. Finally, the regulatory environment remains fluid, with potential for further trade restrictions, changes in spectrum policy, or shifts in digital sovereignty initiatives that could impact supply chains and market access. Navigating these uncertainties requires continuous monitoring, scenario planning, and agile strategic responses.
PW Consulting
Strategic Guidance for Decision-Makers
The optical transceivers market offers substantial opportunities for those who can align their strategies with the underlying drivers of demand, technological change, and regulatory evolution. The following actions provide a starting point for manufacturers, investors, and procurement organizations seeking to capitalize on this dynamic environment.
For Manufacturers and Technology Providers
Invest in scalable manufacturing capabilities that can support high-speed lane rates while maintaining stringent quality and yield targets. Modular architectures that allow for flexibility across form factors and speeds may provide a hedge against standards volatility. Strengthen supply chain resilience by diversifying sourcing, exploring regional production options, and developing contingency plans for component availability. Differentiate through value-added features such as security, power efficiency, and integration support, particularly for customers building AI and high-performance computing infrastructure. Monitor co-packaged optics and silicon photonics developments closely, as these technologies may reshape the competitive landscape and create opportunities for new product categories.
For Investors and Financial Stakeholders
Evaluate companies based on their ability to execute on high-growth segments such as 800G and 1.6T transceivers, their manufacturing scalability, and their exposure to resilient demand applications like AI data centers. Consider the geographic diversification of their supply chains and their alignment with regional digital infrastructure initiatives as indicators of long-term sustainability. Assess R&D pipelines and partnerships that provide access to next-generation technologies, as technological leadership will be a key determinant of market share in a concentrated industry. Recognize that the market may see periods of volatility as standards mature and adoption cycles vary, requiring a balanced view of near-term execution and long-term positioning.
For Procurement and Network Operators
Develop a multi-vendor strategy that balances performance requirements with supply chain risk mitigation. Engage early with suppliers on roadmap alignment, particularly for high-speed transceivers that may impact system design and thermal management. Evaluate total cost of ownership, including power consumption and operational efficiency, rather than focusing solely on unit price, as energy costs and density constraints become increasingly important in high-density deployments. Stay informed about evolving standards and regulatory developments that could affect component availability, compliance requirements, and regional sourcing options. Building relationships with suppliers that offer transparency, flexibility, and advanced feature sets can provide strategic advantages in managing network evolution.
Navigating the Opportunity Horizon
The optical transceivers market is at a pivotal moment where sustained demand growth intersects with rapid technological advancement and shifting geopolitical dynamics. The projected market expansion through the end of the decade underscores the strategic importance of optical connectivity in the broader digital infrastructure ecosystem. However, realizing value in this environment requires more than recognizing the growth trajectory; it demands a nuanced understanding of the competitive landscape, supply chain realities, and the specific technological and regulatory factors that will shape outcomes.
For stakeholders seeking to deepen their understanding of market segments, regional nuances, company-specific profiles, and detailed forecasts, accessing comprehensive research reports can provide the granular data and customized insights needed to refine strategies. Detailed segmentation data, competitive benchmarking, and scenario analysis can help translate high-level trends into actionable plans tailored to specific business contexts. Engaging with specialized market intelligence allows decision-makers to move from general awareness to precise execution, ensuring that investments and initiatives are aligned with the most relevant opportunities and risks in the optical transceivers market.
For detailed analysis of this topic, please visit the official page: Optical Transceivers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Spray Dryer Market 2026: Why 6.51% CAGR and Food & Dairy Applications Reshape Competition
By PW Consulting, 2026-09-21
The Spray Dryer Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global spray dryer market has transitioned from a mature, steady-growth segment into a strategically contested space where capital intensity, regulatory tightening, and end-market demand shifts are reshaping competitive dynamics. Between 2020 and 2025, total market revenue expanded from approximately USD 4.6 billion to USD 6.6 billion, reflecting a compound annual growth rate of roughly 6.5 percent. Forward projections indicate that the segment will approach USD 8.3 billion by the end of the decade and surpass USD 10.2 billion by 2032. This trajectory is not merely a function of incremental capacity additions; it signals a structural revaluation of spray drying as a critical enabling technology across food, pharmaceutical, and specialty chemical production. For executives and investors, the central question is no longer whether demand will grow, but where margin pools will form, which technological pathways will win, and how regulatory and cost pressures will filter the competitive field.
Market Size, Growth Profile, and Structural Constraints
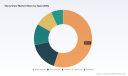
The revenue expansion observed over the past half-decade has been uneven, with a pronounced acceleration in the most recent years followed by a continued upward slope into the forecast window. The 2025 baseline of USD 6.59 billion anchors a forecast period that projects sustained mid-single-digit to high-single-digit growth through 2032. This scale places the market in a position where individual flagship installations can move the needle for equipment vendors, while recurring demand for retrofits, capacity expansions, and process upgrades creates a multi-layered revenue stream. The growth is broad-based across application areas, but the composition matters: food and dairy applications remain the largest revenue pool, pharmaceutical spray drying represents a high-value, compliance-intensive segment, and chemical and specialty applications contribute a smaller but strategically important share tied to ingredient engineering and material science.
Despite the favorable top-line trajectory, the industry faces structural friction that will define investment returns over the next several years. First, spray drying remains an energy-intensive process, and large-scale equipment often carries capital and operating costs that run into multiple millions of dollars. In an environment where industrial energy prices, carbon compliance, and total cost of ownership are scrutinized more closely, buyers are increasingly evaluating not just throughput but lifecycle economics. Second, effective operation demands trained personnel for maintenance, cleaning, and sanitation to preserve product quality and safety. As labor availability and skill constraints tighten in several industrial markets, the operational burden of complex drying lines becomes a hidden cost driver that influences procurement decisions and vendor selection. Third, the market exhibits meaningful concentration, with a small group of established players commanding a substantial share of revenue. This concentration creates both stability and friction: incumbents benefit from installed bases, service relationships, and scale, while newer or smaller entrants face higher barriers to displace them without a clear technology or cost advantage.
Food Dryer Market
Key Challenges and Turning Points
The market is currently navigating three interrelated turning points that will separate resilient operators from those left behind. The first is the growing tension between throughput ambition and sustainability expectations. Buyers are expanding production to capture demand in dairy powders, instant coffee, and emerging plant-based ingredients, yet they are simultaneously pressured to reduce energy intensity, water consumption, and waste. Equipment that cannot demonstrate measurable efficiency gains or that complicates compliance with environmental and quality standards risks becoming a liability rather than an asset. The second turning point is regulatory harmonization and its operational implications. Recent rule changes that align quality management expectations with recognized international standards for medical device and pharmaceutical manufacturing have raised the bar for documentation, validation, and process control. For spray dryer vendors and end-users alike, this means that engineering excellence alone is insufficient; systems must be designed, qualified, and operated within validated design spaces that satisfy increasingly rigorous oversight. The third turning point is the shift from standardized equipment purchases toward integrated, application-specific solutions. End-users are less interested in commoditized drying capacity and more focused on achieving consistent particle morphology, moisture control, and throughput stability tailored to their formulations. This shift rewards vendors who can combine atomization precision, automation, and process analytics into a coherent solution, while penalizing those who compete primarily on baseline specifications.
Key Drivers Shaping the Spray Dryer Market
Technological Innovation and Process Control
Technology differentiation is becoming the primary lever for margin protection and competitive separation. Advanced atomization methods, improved heat recovery, and tighter integration of process analytics are redefining what a spray dryer can deliver beyond simple drying. In pharmaceutical and high-value food applications, particle size distribution, bulk density, and reconstitution behavior are decisive quality attributes, and equipment that can hold these parameters within narrow tolerances commands a premium. The rise of automated control architectures and real-time monitoring is reducing variability and shortening qualification cycles, which matters enormously in regulated environments where design space optimization and process validation are mandatory. Recent equipment activity underscores this direction: a major supplier introduced an advanced pharmaceutical spray dryer to a prominent biologics manufacturer to strengthen product development and manufacturing capabilities, signaling how targeted technology deployment can open high-value account relationships. At the same time, laboratory and pilot-scale installations continue to play a strategic role, with research institutions and advanced materials groups commissioning new drying units to separate solids from liquids or suspensions into powder with greater efficiency and reproducibility. These smaller-scale deployments are not merely academic; they feed the innovation pipeline that later scales into commercial lines, making pilot equipment a leading indicator of where application technology will move next.
Policy, Regulatory Environment, and Quality Expectations
The regulatory backdrop is reshaping procurement criteria and vendor qualification processes. The effective integration of recognized quality management system standards for medical device manufacturers, including spray dryers used in pharmaceutical production, has elevated expectations for documentation, traceability, and validated operating envelopes. In parallel, guidelines emphasizing process validation and design space optimization for pharmaceutical spray drying require vendors and operators to demonstrate that their processes can consistently deliver quality outcomes within defined parameters. These requirements are not isolated compliance exercises; they influence capital planning, installation timelines, and the total cost of ownership. Buyers are increasingly factoring in the cost of qualification, the risk of rework, and the operational burden of maintaining auditable records. For equipment makers, this environment favors organizations that can embed quality-by-design principles into their hardware and software, provide robust validation support, and maintain long-term service relationships that help clients sustain compliance over multi-year lifecycles. The regulatory trend also raises the stakes for cross-border sourcing, as manufacturers evaluate whether equipment and support from different regions can meet the documentation and oversight expectations of the markets they serve.
PW Consulting Automotive & Machinery Research Center
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being reshaped by both consumer-facing trends and enterprise formulation strategies. In food and dairy, the continued expansion of shelf-stable powders, instant formats, and functional ingredients sustains core demand, while the emergence of plant-based and alternative protein ingredients adds new complexity to drying requirements. Formulators are seeking powders with specific solubility, dispersibility, and sensory profiles, which pushes equipment selection toward systems that can handle sensitive materials without thermal degradation and that can be cleaned and reconfigured efficiently. In pharmaceuticals, the drive toward more complex biologics, specialized intermediates, and precise delivery forms increases the value of drying processes that preserve activity and deliver repeatable quality. Enterprises are also placing greater emphasis on supply chain resilience and regional production footprints, a shift that encourages capacity additions closer to end markets and favors vendors who can deliver localized engineering support, spare parts availability, and service responsiveness. The combined effect is a demand environment that values reliability, flexibility, and application expertise as much as raw capacity.
Supply Chain, Cost Structure, and Operational Realities
Cost structure is increasingly a strategic variable rather than a background condition. Because large-scale spray drying systems involve significant capital outlay and ongoing energy consumption, buyers are extending their evaluation windows to include installation risk, commissioning complexity, and long-term operating expense. Trained operators and maintenance teams are essential for regular cleaning, sanitation, and performance upkeep, which means labor skill constraints can directly affect availability and throughput. In this context, vendors that offer integrated automation, straightforward cleaning protocols, and predictable maintenance cycles can reduce hidden costs and improve customer economics. The supply side is also influenced by the geography of manufacturing and service networks. Established suppliers with strong regional presence can shorten lead times and improve responsiveness, while emerging manufacturers may compete on price or specialized features but must demonstrate reliability in execution and support to win and retain large accounts. Cost pressure does not necessarily compress the entire market uniformly; instead, it tends to bifurcate purchasing behavior, with some buyers optimizing for upfront price and others prioritizing total lifecycle value and risk reduction.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is anchored by a set of established companies that combine engineering heritage, application knowledge, and service infrastructure. A German-based group provides specialized spray drying solutions for dairy, food ingredients, pharmaceutical, and instant coffee production, emphasizing integrated plant designs and process know-how that extend beyond the dryer itself. A major U.S.-headquartered flow control and processing company offers spray dryer systems under a well-recognized brand for food, dairy, and pharmaceutical powders, with a focus on advanced atomization and process technology. A Swiss laboratory technology manufacturer manufactures laboratory and pilot-scale units for research, quality control, and small-scale pharmaceutical and chemical applications, positioning itself at the upstream end of the innovation and validation chain. A German engineering firm supplies customized industrial spray dryers for food, chemical, and starch industries, offering pilot to full-scale units built on decades of experience and a customization-first philosophy. A U.S.-based developer focuses on pulse atomization spray dryers aimed at energy-efficient drying across food, chemical, mineral, and pharmaceutical powders, differentiating through a specific energy-saving technology pathway. A Swiss packaging and processing solutions provider delivers automated spray drying systems for dairy, whey, and plant-based powders using wide-body technology, aligning drying equipment with broader integrated processing lines. A Chinese manufacturer produces milk and food spray dryers with precision engineering and automation tailored to dairy applications, reflecting the growing capability and regional demand base in Asia. A U.S. manufacturer supplies domestically produced spray dryers for starch, food, and industrial powder production, catering to customers that prioritize local engineering and supply chain continuity.
These companies are not competing on a single axis. Incumbents with broad application portfolios leverage installed bases, service networks, and cross-selling into upgrades and retrofits. Technology specialists compete by proving measurable advantages in energy efficiency, particle control, or process robustness. Laboratory and pilot-scale providers maintain a strategic foothold by supporting qualification, method development, and scale-up, which positions them as trusted partners when commercial projects move forward. The differentiation that matters most in the current environment is the ability to reduce variability, accelerate qualification, and support compliance over the life of the equipment, rather than simply offering competitive baseline pricing.
Worldwide Freeze Drier Market
Evolution of Market Structure
The competitive structure is evolving along two parallel tracks: consolidation of advantage among well-positioned incumbents, and selective entry by specialists targeting high-value niches. Concentration in the market remains significant, which means that large accounts often engage with a limited set of trusted suppliers for major capital projects. This dynamic reinforces the importance of reputation, reference installations, and the ability to deliver complex projects on schedule. At the same time, the demand for application-specific solutions and energy-efficient designs creates openings for companies that can demonstrate a clear performance edge or a compelling total cost proposition. Newer entrants and regional manufacturers are most likely to succeed where they can pair technical differentiation with reliable execution and after-sales support, rather than competing solely on hardware price. Over time, the market is likely to see further rationalization, with stronger players capturing share through integrated offerings and service-led relationships, while smaller players either niche down into specific applications or exit segments where scale and compliance costs are prohibitive.
Future Trends and Commercial Implications (2026–2032)
Trend One: Efficiency as a Default Requirement, Not a Bonus Feature
Energy intensity will move from a cost consideration to a design requirement. As buyers confront both operating expense pressure and sustainability expectations, spray drying systems that incorporate efficient heat recovery, optimized atomization, and lower standby losses will gain preference. This trend favors vendors that can quantify efficiency gains in operational terms and integrate those claims into a credible total cost narrative. Commercially, this creates opportunities for retrofits, control upgrades, and selective replacements that improve throughput per unit of energy, particularly in mature dairy and food ingredient facilities where marginal efficiency improvements translate directly into margin. The risk is that efficiency claims become a crowded field; differentiation will depend on verifiable performance data, installation reality, and the ability to maintain efficiency over time rather than only at commissioning.
Trend Two: Compliance-Integrated Equipment and Service Models
Regulatory expectations will continue to pull quality management deeper into equipment selection and operation. As pharmaceutical and related applications require validated design spaces, rigorous documentation, and consistent process control, the economic value of equipment that supports these requirements will rise. Vendors that can provide structured qualification support, auditable configuration management, and long-term service that helps clients sustain compliance will strengthen customer stickiness. This trend also encourages broader service and lifecycle contracts, where revenue is tied not only to hardware sales but to ongoing performance assurance and regulatory readiness. The uncertainty lies in the pace and specifics of regulatory evolution across regions, which can shift qualification burdens and affect project timelines. Companies that maintain regulatory flexibility and invest in documentation and validation capabilities will be better positioned to adapt.
Trend Three: Application-Specific Flexibility and Regional Capacity
Demand will increasingly reward flexibility and regional responsiveness over one-size-fits-all capacity. Formulators in food, dairy, and emerging plant-based segments will require systems that can handle varied materials, support cleaning and changeover, and produce consistent powder characteristics across batches. At the same time, supply chain resilience considerations will encourage capacity additions closer to end markets, particularly where regional production reduces logistics risk and improves service proximity. Commercially, this trend opens opportunities for modular designs, pilot-to-production pathways, and vendors that can deliver localized engineering and maintenance support. The principal risk is that excessive customization can raise cost and complexity; the winning approach will balance flexibility with standardized core architectures that keep qualification and maintenance manageable.
Strategic Actions for Decision Makers
For Manufacturers and Equipment Vendors
Invest in efficiency and compliance as core product attributes. Differentiation based solely on capacity or baseline features is increasingly insufficient; instead, develop demonstrable advantages in energy performance, particle control, automation, and validation support. Build service-led revenue streams that help customers sustain quality and efficiency over the lifecycle of the equipment, because recurring support relationships often determine long-term share more than the initial sale. Where regional demand is expanding, consider localized engineering and spare parts capabilities that reduce lead times and improve customer confidence, while retaining a standardized core platform to control cost and qualification complexity.
For Investors and Strategic Allocators
Focus on the segments and business models where regulatory and efficiency tailwinds concentrate value. Pharmaceutical and high-value food applications offer stronger pricing power for equipment and services that reduce variability and accelerate qualification, while volume-driven food and dairy segments reward efficiency improvements and lifecycle support. Evaluate companies not only by headline revenue but by their ability to win and retain complex accounts, support compliance, and convert installed bases into upgrades and service contracts. Monitor the pace of regulatory alignment and energy economics, as both will influence project timing, procurement criteria, and the relative attractiveness of technology-led versus price-led competition.
For Procurement and Operations Leaders
Extend the evaluation framework beyond purchase price to total lifecycle economics and risk. Include energy consumption, cleaning and sanitation burden, qualification and documentation requirements, spare parts availability, and service responsiveness in the decision process. Where compliance intensity is high, prioritize vendors that can provide structured validation support and predictable operating performance, because the cost of rework, downtime, or audit findings can outweigh marginal hardware savings. Consider phased adoption paths that use pilot or laboratory-scale units to de-risk formulation and process choices before committing to large-scale capital, especially when material sensitivity or particle quality is critical to the final product.
The spray dryer market is entering a period in which technical precision, regulatory readiness, and operating economics will determine competitive outcomes as clearly as capacity expansion ever did. The growth trajectory through 2032 is robust, but the distribution of value will favor organizations that can align equipment performance with the practical realities of energy cost, compliance, labor skill, and application flexibility. For leaders navigating capital allocation, vendor selection, or market entry, the most valuable intelligence is granular: segment-level demand shifts, technology adoption curves, regional service dynamics, and the evolving qualification burden in regulated applications. Detailed research that breaks down these dimensions by application, equipment type, and region can clarify where to commit capital, which vendors to qualify, and how to sequence investments for the next cycle of demand.
For detailed analysis of this topic, please visit the official page: Spray Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Diodes Market: Why Secure Unidirectional Flow Drives 7.15% CAGR Toward $349M in Revenue
By PW Consulting, 2026-09-21
The Data Diodes Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Landscape: Size, Trajectory, and Structural Challenges
Data diodes have moved from niche secure-transfer tools into mainstream components of enterprise and critical infrastructure security postures. The market reached USD 215.75 million in 2025, having grown steadily from 160.25 million in 2020. Forward projections indicate a compound annual growth rate of 7.15 percent through 2032, with revenue expanding to USD 349.05 million by the end of the forecast period. This trajectory reflects a structural shift: organizations are no longer treating unidirectional transfer as an edge-case compliance requirement, but as a foundational layer for cross-domain data exchange, operational technology isolation, and forensic integrity.
The growth curve is not uniform. Historical momentum from 2020 to 2025 was supported by defense modernization programs, energy sector cybersecurity mandates, and early industrial automation deployments. From 2026 onward, the pace accelerates as data diodes embed into broader security architectures, not as standalone hardware purchases but as integrated safeguards within OT/IT bridging, cloud replication, and incident response workflows. The market’s resilience across economic cycles underscores a key insight: data diodes solve a persistent, non-negotiable problem—secure one-way movement of information between networks with differing trust levels—and that problem is only expanding as connectivity widens.
Key Challenges and Inflection Points
Three structural challenges are shaping how the market evolves and where commercial value concentrates.
First, the tension between assurance and usability. Customers increasingly demand diodes that deliver hardware-enforced one-way transfer without imposing heavy operational burdens. Traditional deployments required meticulous protocol matching, manual rule sets, and specialized integration expertise. Newer solutions are compressing that complexity, but the bar for "plug-and-play" assurance remains high, especially in defense, rail, water, and industrial control environments where failure is not an option. The inflection point is arriving as vendors pair physical unidirectionality with protocol-level intelligence, allowing organizations to preserve security while reducing deployment friction.
Second, the labor and process cost of legacy data handling. Manual transport and retrieval of physical media for data movement carries annual costs ranging from USD 2,100 to USD 10,000 per workflow, with labor-intensive processes that are error-prone and difficult to scale. As organizations digitize operations and expand cross-domain data sharing, these manual workarounds become unsustainable. The challenge for buyers is not only switching to automated unidirectional transfer, but doing so in a way that integrates with existing SCADA, historian, and cloud replication pipelines without creating new operational silos.
PW Consulting Information & Electronics Research Center
Third, certification and regulatory alignment as both enabler and gatekeeper. Data diodes align with guidance such as NIST 800-82 for unidirectional gateways in OT/ICS environments, helping prevent lateral movement in critical infrastructure. At the same time, government and defense buyers require validated, often certified, assurance levels that vary by jurisdiction and classification. This creates a dual dynamic: regulation expands the addressable market by mandating stronger isolation, while certification requirements raise the entry threshold for new suppliers and slow procurement in highly regulated segments. The market is therefore bifurcating between high-assurance, certified solutions for government and defense, and more agile, lower-friction offerings for commercial OT and enterprise IT.
Core Drivers Shaping the Market
Technological Innovation and Breakthroughs
The most consequential technical shift is the fusion of hardware-enforced unidirectionality with protocol filtering and software-defined integration. Early data diodes prioritized raw one-way transfer, often at the cost of protocol compatibility and operational visibility. Recent product moves show a clear pivot toward intelligent unidirectional gateways that understand specific protocols, filter traffic at the hardware or firmware level, and interoperate with operational software stacks. This reduces the need for custom middleware and allows organizations to move operational data from OT to IT or cloud environments with assurance intact.
A second innovation vector is form factor and deployment flexibility. Pocket-sized incident response diodes for forensic evidence collection, card modules for embedded applications, and DIN-rail appliances for industrial networks illustrate how vendors are tailoring hardware to specific use cases rather than offering one-size-fits-all appliances. This modularity is expanding adoption beyond large, centralized security projects into edge, trackside, and distributed industrial settings where space, ruggedness, and rapid deployment matter.
A third vector is assurance certification paired with performance. Solutions validated for high-assurance one-way transfer at speeds up to 100 Gbps demonstrate that security and throughput are no longer traded off. For buyers, this matters because high-speed cross-domain replication is increasingly required for real-time operational monitoring, centralized analytics, and disaster recovery workflows that cannot tolerate latency or manual handoffs.
Policy and Regulatory Environment
Policy is a primary demand accelerator. In OT and ICS environments, guidance that emphasizes unidirectional gateways to prevent lateral movement directly supports data diode adoption. In government and defense, validated protocol filtering and classification-grade certifications create procurement pathways for suppliers that meet stringent assurance requirements. The practical effect is twofold: regulators and standards bodies are normalizing unidirectional transfer as a best practice, and certified products are gaining preferential access to high-value public sector and critical infrastructure contracts.
At the same time, regulatory diversity creates fragmentation. Different jurisdictions and program offices emphasize different certification regimes, from national armed forces standards to common criteria evaluation assurance levels and sector-specific OT guidance. Suppliers that can navigate this mosaic—and articulate how their hardware and software stack maps to each requirement—are gaining trust and shortening sales cycles in regulated segments. Buyers, conversely, are increasingly specifying assurance requirements up front, which rewards suppliers with transparent certification posture and documented integration paths.
Demand-Side Shifts in Enterprise and Industrial Behavior
Demand is expanding beyond defense and government into commercial OT, energy, water, manufacturing, and rail. Several behavioral shifts are driving this. Organizations are moving from periodic, manual data exchange to continuous, automated operational data replication for monitoring, analytics, and cloud integration. They are also treating cross-domain transfer as a design-time requirement rather than a retrofit, embedding unidirectional safeguards into network segmentation strategies from the outset.
In industrial settings, the rise of protocol-aware appliances that support OPC UA and MQTT reflects a demand for secure, standards-based connectivity between operational networks and higher-level IT or cloud systems. In water and wastewater, integrations with SCADA software illustrate demand for reliable one-way transfer that preserves operational integrity while enabling centralized visibility. In rail, trackside-specific diodes compliant with sector standards show demand for rugged, low-maintenance solutions in harsh, distributed environments. Across these cases, the common thread is trust: organizations want to share data outward without exposing inward paths, and they want to do so without rebuilding operational workflows.
Supply Chain and Cost Structure Dynamics
Cost dynamics are shifting from pure hardware price to total cost of ownership and operational efficiency. Manual data transport workflows carry hidden costs in labor, error risk, and scheduling overhead, which makes automated unidirectional transfer attractive even before considering security benefits. Suppliers that reduce deployment complexity, minimize software dependencies, and integrate with existing operational tools are lowering the practical cost of adoption.
On the supply side, ruggedized hardware and certified components introduce procurement complexity, but they also create differentiation. Vendors that combine TEMPEST and RÖS-grade rugged data diodes, card modules, and tamper-proof hardware with clear certification documentation are positioning themselves for segments where assurance outweighs cost sensitivity. Meanwhile, commercial OT and enterprise buyers are increasingly weighing ease of deployment, protocol compatibility, and integration support alongside raw assurance, creating room for differentiated offerings that optimize for different buyer priorities.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three players holding roughly 26.5 percent of revenue and the top five approaching 32.8 percent. This concentration indicates a fragmented but maturing field: established specialists hold meaningful share in high-assurance segments, while a broader set of entrants competes on integration, usability, and vertical-specific fit. The strategic question for buyers and investors is not who leads today, but which differentiation paths will compound over the next several years.
Strategic Positioning and Differentiation Among Leading Players
Owl Cyber Defense has built a strong U.S. government-aligned position around protocol filtering diodes and incident response diodes for high-assurance one-way transfer. Its February 2026 validation of the Talon Torrent as an approved protocol filtering diode for reliable one-way transfer up to 100 Gbps signals that throughput and assured filtering can coexist. The May 2026 launch of a pocket-sized incident response diode for forensic evidence collection from compromised endpoints using USB with hardware-enforced one-way protocol filtering shows a move toward portable, task-specific assurance. The June 2026 integration of VTScada SCADA software with data diodes for secure one-way operational data transfer from OT to IT/cloud in water and wastewater deployments in Houston and Nashville illustrates a push into vertical-specific, software-integrated deployments.
OPSWAT positions around unidirectional gateways that couple data diode hardware with file sanitization and cross-domain secure data replication for IT/OT isolation. Its MetaDefender Optical Diode and related offerings emphasize content-aware protection at the transfer boundary, which appeals to buyers who want assurance plus malware handling and content control in one workflow. This strategy broadens the use case beyond pure unidirectionality into content security, which can reduce the number of discrete tools an organization must integrate.
Rectifier Diode Market
Fibersystem AB and Advenica represent the high-assurance, ruggedized flank of the market. Fibersystem focuses on TEMPEST Level A+ and RÖS U1 rugged data diodes and card modules for secure, high-assurance one-way transfer, targeting environments where electromagnetic emissions and physical hardening matter. Advenica offers a family of data diodes with N3 Swedish Armed Forces certification for top-secret to qualified secret levels, signaling deep government-grade assurance. Advenica’s March 2026 launch of a data diode engineered for railway trackside applications, compliant with EN railway standards and requiring no additional security software, shows how assurance players can expand into vertical-specific, low-maintenance deployments without sacrificing certification posture.
Patton Electronics emphasizes industrial network fit with the FiberPlex FP-DD100 DIN-rail ultra-secure data diode, supporting OPC UA and MQTT protocols. Its October 2025 launch reflects a strategy of embedding unidirectional transfer into industrial automation infrastructures where protocol compatibility and form factor are decisive. BAE Systems brings Common Criteria EAL 7+ certified data diode solutions for secure cross-domain transfer between networks of differing trust levels, leveraging defense-scale credibility and high assurance evaluation. Waterfall Security Solutions combines hardware diodes with software for industrial OT/ICS environments, operationalizing unidirectional transfer within broader industrial security architectures.
ST Engineering offers endpoint data diodes certified with CC EAL 4+ and NITES for industrial and defense use, balancing assurance with accessibility. Nexor provides tamper-proof hardware data diodes for secure classified information transfer between trusted and untrusted networks, reinforcing a classified-transfer niche. Garland Technology contributes data diode TAPs for one-way raw data flow in industrial and network monitoring applications, extending unidirectional concepts into visibility and segmentation infrastructure. Valiant Communications supplies hardware data diodes for secure one-way network communication in cybersecurity environments, while Everfox focuses on unidirectional data diode solutions for cross-domain secure transfers with reduced TCO and easy deployment, explicitly targeting cost and operational simplicity.
Market Evolution: Integration, Specialization, and New Entrants
The competitive landscape is evolving along three vectors. First, integration is becoming a primary differentiator. Suppliers that pair hardware unidirectionality with protocol intelligence, SCADA or historian integration, and content security are capturing buyers who want fewer integration points and clearer operational outcomes. Second, specialization by vertical and environment is sharpening. Rail, water, industrial automation, and defense each impose distinct standards, environmental constraints, and assurance expectations, rewarding vendors that engineer for those contexts rather than offering generic appliances. Third, new entrants and adjacent players are competing on usability and TCO, particularly in commercial OT and enterprise settings where deployment speed and integration effort matter as much as certification.
ESD Protection Diode Market
Consolidation pressure is likely to increase as larger security and industrial technology firms seek to own the cross-domain transfer layer within broader platforms. At the same time, fragmentation will persist because assurance requirements, environmental ruggedness, and vertical standards create niche moats. The practical implication is that buyers will encounter both platform plays and specialist solutions, and the right choice will depend on whether the priority is high-assurance certification, vertical fit, or rapid integration with existing operational tooling.
Forward Outlook: Three Trends to Watch (2026–2032)
Trend 1: From Point Solutions to Embedded Cross-Domain Architectures
Data diodes are shifting from standalone appliances to embedded components within cross-domain architectures. Buyers increasingly expect unidirectional transfer to interoperate with operational software, cloud replication, and network segmentation frameworks. This trend expands the addressable need because it turns data diodes from a compliance checkbox into a design element for secure data movement across OT, IT, and cloud domains. Commercial opportunities will accrue to suppliers that offer validated integration paths, reference architectures, and vertical-specific templates that reduce deployment risk. The risk is that integration breadth can outpaced assurance depth if vendors overpromise compatibility without rigorous validation.
Trend 2: Protocol-Aware, High-Throughput Assurance Becomes Table Stakes in Regulated Segments
High-assurance one-way transfer at speeds up to 100 Gbps, combined with hardware-enforced protocol filtering, is becoming a baseline expectation in defense and critical infrastructure. As operational data volumes grow and real-time monitoring becomes standard, organizations cannot afford latency or manual handoffs. The opportunity lies in solutions that preserve assured unidirectionality while supporting the protocols and throughput that modern operations demand. The uncertainty is regulatory: as standards evolve, certification requirements may tighten or diversify, affecting which products qualify for high-value contracts and how quickly procurement cycles move.
Trend 3: Vertical-Specific, Ruggedized, and Low-Maintenance Deployments Expand the Addressable Market
Trackside rail diodes, DIN-rail industrial appliances, pocket-sized forensic diodes, and rugged card modules illustrate a broader move toward environment-specific, low-maintenance deployments. This trend opens markets that were previously underserved by high-end, centralized appliances, including distributed industrial sites, remote operational environments, and incident response scenarios that require rapid, portable evidence collection. The commercial upside is volume growth in verticals that value ruggedness, standards compliance, and minimal software dependency. The downside risk is supply complexity: ruggedized and certified variants can raise manufacturing and procurement overhead, and vertical standards may differ enough to fragment product lines.
Strategic Recommendations for Decision-Makers
For Manufacturers and Technology Providers
- Align product roadmaps with protocol-aware, high-throughput assurance and vertical-specific form factors. Customers in OT, rail, water, and industrial automation are prioritizing deployment fit and integration readiness alongside assurance, so differentiated value will come from validated protocol support, ruggedized options, and reference integrations.
- Invest in certification transparency and integration documentation. In regulated segments, the ability to map hardware and software to relevant assurance frameworks shortens evaluation cycles and builds trust. Clear documentation of how a solution supports unidirectional gateways in OT/ICS contexts and meets sector-specific standards reduces buyer risk.
- Balance platform breadth with niche moats. Consider whether to pursue integrated cross-domain platforms or deepen vertical and environmental specialization. Both paths can work, but clarity of positioning matters more than breadth alone.
For Investors
- Focus on suppliers that combine assurance with usability and vertical fit. The market’s growth is increasingly driven by integration, protocol intelligence, and environment-specific deployments, so companies that reduce operational friction while preserving hardware-enforced security are better positioned to capture recurring and expanded deployments.
- Watch certification milestones and government-validated approvals as catalysts. Validated protocol filtering diodes and classification-grade certifications can unlock high-value segments and improve competitive positioning, making them meaningful indicators of near-term demand potential.
- Assess total cost of ownership narratives, not just hardware pricing. Solutions that lower manual process costs, simplify deployment, and reduce software dependency can win in commercial OT and enterprise settings where buyers weigh operational efficiency alongside security.
For Procurement and Security Leaders
- Define assurance requirements and integration needs up front. Specify the trust levels, certification expectations, protocols, and operational software interfaces that matter for your environment. This reduces evaluation risk and helps suppliers propose solutions that fit rather than forcing generic compromises.
- Treat unidirectional transfer as part of network segmentation strategy, not an isolated purchase. Data diode TAPs and unidirectional gateways can support raw data flow and lateral movement prevention when embedded thoughtfully into segmentation designs, improving both security and operational visibility.
- Evaluate total cost and operational impact, including legacy manual processes. Automated one-way transfer can reduce labor-intensive handling and error risk, so consider the full workflow cost when comparing solutions. Solutions that minimize additional security software dependencies may be preferable in rugged or distributed environments where maintenance overhead is a concern.
Closing Perspective
The data diodes market is entering a phase where growth is driven less by isolated security purchases and more by the embedding of unidirectional transfer into cross-domain, vertical-specific, and operationally integrated architectures. The numbers tell a clear story of expansion, but the strategic story is about fit: assurance that matches the environment, protocol intelligence that matches the workflow, and deployment models that match the operational reality. As certification requirements evolve, vertical standards tighten, and integration expectations rise, the suppliers and buyers who succeed will be those who treat unidirectional transfer as a design principle rather than a point solution. For decision-makers seeking detailed segmentation data, regional nuances, and tailored recommendations, the full research report provides the deeper breakdown needed to align investment and procurement decisions with the market’s direction.
For detailed analysis of this topic, please visit the official page: Data Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isophthalonitrile Market 2026: 5.5% CAGR and the Real Drivers Shaping Demand to 2032
By PW Consulting, 2026-09-21
Isophthalonitrile (INP) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Isophthalonitrile (INP) market has demonstrated steady expansion over the past half-decade, evolving from a specialized chemical intermediate into a strategically significant segment tied to advanced materials and agrochemical supply chains. Valued at approximately $163.15 million in 2020, the market grew to $215.0 million by 2025, reflecting a compound annual growth rate of 5.5 percent. Projections through 2032 indicate the market will surpass $311 million, driven by accelerating demand in high-performance polymers, pharmaceutical intermediates, and specialty crop protection formulations. While the trajectory appears consistent, the underlying dynamics reveal a market at an inflection point, where growth is no longer guaranteed by volume alone but increasingly dependent on technological adaptation, regulatory navigation, and supply chain resilience.
Several structural challenges are shaping how market participants operate today. First, the concentration of supply among a handful of established producers creates both stability and vulnerability. With the top three and top five players collectively controlling the majority of global output, pricing power and capacity allocation are heavily influenced by strategic decisions from a small group of manufacturers. This concentration limits the ability of downstream buyers to negotiate favorable terms during periods of tight supply, while simultaneously raising the barrier for new entrants seeking to achieve meaningful scale.
Second, raw material price volatility continues to disrupt cost forecasting and margin stability. The production of INP relies on specialized precursor chemistry, and fluctuations in petrochemical feedstocks, energy costs, and catalytic materials introduce unpredictable swings in manufacturing expenses. These swings are particularly acute for producers operating in regions with less diversified supply networks or weaker hedging capabilities, forcing them to balance competitive pricing against the risk of margin compression.
Third, the regulatory environment is becoming increasingly complex, especially for producers and exporters navigating cross-border material controls. Recent export restrictions on critical semiconductor-related materials in major Asian markets have introduced uncertainty into broader chemical supply chains, prompting buyers and manufacturers alike to reassess sourcing strategies, inventory buffers, and alternative formulation pathways. These overlapping pressures mean that simply tracking market size is insufficient; understanding how capacity, regulation, and input costs interact is essential for making informed commercial decisions.
Worldwide 4-Brombenzonitrile Market
Key Drivers Shaping Market Trajectories
Technological Innovation and Process Optimization
Advancements in synthetic chemistry and manufacturing efficiency are reshaping the value proposition of INP across multiple end-use sectors. Improved catalytic processes and purification techniques have enabled producers to achieve higher consistency at elevated purity levels, which matters significantly for applications in synthetic resins and electronic-grade materials where impurity tolerances are extremely tight. As downstream manufacturers demand more reliable specifications, suppliers that invest in process control, analytical quality assurance, and continuous improvement are positioned to capture premium segments rather than competing solely on price.
Beyond purification, innovation is also expanding the practical utility of INP in higher-margin applications. Research into advanced polymer architectures and specialty intermediates has reinforced the role of INP as a foundational building block for m-xylylenediamine and related derivatives, which in turn support high-performance engineering plastics and coatings. The convergence of material science requirements and chemical manufacturing capability is creating a positive feedback loop: as end-use applications become more demanding, the incentive to invest in better production methods grows, and those investments in turn unlock new commercial pathways.
Policy and Regulatory Evolution
The regulatory landscape is no longer a background condition; it is a direct determinant of market access, sourcing flexibility, and long-term planning. Export controls and material security policies in several key production regions have already begun influencing how chemical manufacturers structure their supply networks. While these measures are often framed around critical minerals and compound semiconductors, their ripple effects extend into adjacent chemical markets where reliability of supply, traceability, and compliance documentation are increasingly scrutinized.
For INP market participants, this means that regulatory readiness is becoming a competitive attribute. Companies that proactively align with evolving export compliance requirements, maintain transparent documentation practices, and diversify their customer base across jurisdictions are better positioned to avoid disruption. At the same time, regulatory divergence between regions can create uneven playing fields, where producers in one jurisdiction face different cost structures or approval timelines than those in another. Strategic leaders are treating regulatory forecasting as part of their core operational planning rather than a reactive compliance exercise.
Shifting Demand-Side Behavior
Demand for INP is being shaped less by a single end market and more by a combination of performance requirements across diverse applications. In the agrochemical sector, the push for more targeted and efficient crop protection solutions continues to support steady consumption of specialty intermediates. At the same time, pharmaceutical and fine chemical manufacturers are increasingly looking for reliable, high-specification inputs that can support complex synthesis routes without introducing variability. These demand-side shifts favor suppliers that can offer consistent quality, technical support, and flexible order structures.
There is also a growing preference among downstream buyers for supply partners that can provide visibility into capacity, lead times, and contingency plans. This is not simply a cost consideration; it is a risk-management decision. As global supply chains have become more sensitive to geopolitical tension, logistics disruption, and energy volatility, procurement teams are placing greater weight on reliability and strategic alignment. Suppliers that can demonstrate operational resilience and transparent communication are gaining preferential access to long-term contracts and repeat business.
Supply Chain Restructuring and Cost Dynamics
The cost structure of INP production is being reshaped by broader changes in global manufacturing geography and logistics. Some producers are consolidating operations to achieve economies of scale, while others are expanding or relocating capacity to balance proximity to key customers with access to raw materials and energy. These decisions are not purely about production cost; they are about reducing exposure to transport bottlenecks, aligning with regional regulatory frameworks, and strengthening relationships with end markets.
Simultaneously, the market is witnessing a gradual recalibration of inventory strategies. Buyers that once prioritized minimal inventory and just-in-time procurement are increasingly maintaining strategic buffers for critical intermediates. This shift changes the rhythm of demand signals reaching producers and encourages capacity planning that accounts for both baseline consumption and surge scenarios. The companies that can interpret these signals accurately and adjust production schedules accordingly are gaining an advantage in both service levels and cost efficiency.
Competitive Landscape and Leading Strategies
The competitive environment for INP is defined by a small group of active producers, each pursuing distinct strategic positions based on geography, application focus, and operational strengths. Mitsubishi Gas Chemical Company, Inc. has maintained a notable presence through its focus on synthetic resins and electronics-related applications, leveraging an integrated chemicals business model that emphasizes reliability, quality consistency, and long-term customer relationships. Its positioning reflects an emphasis on high-value applications where specification stability and technical support matter more than bare volume.
In China, Jiangsu Weunite Fine Chemical Co., Ltd. has built its relevance around fine chemical intermediates supporting agrochemicals and electronics, aligning with regional demand patterns and production scale advantages. Its strategy underscores the importance of matching manufacturing capabilities to the application priorities of nearby downstream industries, which can shorten lead times and improve responsiveness. Similarly, Suli Co., Ltd. focuses on pharmaceutical and fine chemical intermediates, positioning itself in segments where purity, documentation, and process control are particularly critical. This application-specific focus illustrates how producers are differentiating not just by price, but by the fit between their technical capabilities and the requirements of their chosen markets.
The market structure is evolving along several axes. On one hand, the concentration of output among leading producers creates a relatively stable but potentially inflexible environment, where incremental capacity additions and quality improvements can have outsized influence on pricing and availability. On the other hand, the growing importance of compliance, specialty applications, and supply reliability is opening space for differentiation that goes beyond conventional scale economies. New entrants or expanding producers that can combine cost discipline with strong technical execution and regulatory readiness have the potential to capture meaningful share in specific segments, particularly where existing supply is constrained or where customers are prioritizing resilience over lowest unit cost.
Strategic leadership in this environment is increasingly defined by the ability to balance multiple priorities simultaneously: maintaining cost competitiveness, investing in process and quality capabilities, managing regulatory exposure, and building trusted relationships with downstream customers. Companies that treat these as interconnected rather than isolated priorities are better equipped to sustain margins and protect market position as the landscape matures.
Forward-Looking Trends and Commercial Opportunities
Over the next three to five years, several trends are likely to shape how value is created and captured in the INP market. One prominent trend is the continuing premiumization of demand in high-specification applications. As electronics-related materials and advanced synthetic resins become more performance-sensitive, the share of demand tied to higher purity and tighter quality assurance is expected to grow. This creates opportunities for producers that can consistently meet elevated specifications and for downstream manufacturers that can secure reliable access to these grades without compromising supply continuity.
A second trend is the deepening role of regulatory and supply chain resilience as commercial differentiators. Buyers are increasingly evaluating suppliers not only on price and volume, but on their ability to provide stable delivery under shifting trade conditions, maintain compliant documentation, and support contingency planning. Suppliers that invest in visibility, flexibility, and compliance infrastructure can translate these capabilities into stronger customer retention and more favorable contract terms. This trend also opens the door for regional supply strategies that reduce exposure to cross-border friction while maintaining access to key demand centers.
PW Consulting
A third trend is the gradual re-balancing of capacity and sourcing strategies as raw material dynamics and energy costs continue to fluctuate. Market participants that diversify input sourcing, strengthen hedging approaches, or align production with regions offering more predictable cost structures will be better positioned to protect margins. At the same time, there is opportunity for producers to capture value by offering application-specific solutions that reduce the total cost of ownership for buyers, rather than competing purely on the headline price of the intermediate itself.
These trends are not without risk. Concentration in supply means that unexpected capacity constraints or strategic decisions by a small number of producers can quickly affect availability and pricing. Raw material volatility remains a persistent threat to cost predictability, particularly if energy prices or precursor availability shift abruptly. Regulatory divergence could also introduce uneven compliance burdens, affecting competitiveness across regions. Companies that prepare for these uncertainties by building flexibility into sourcing, capacity planning, and customer engagement will be better positioned to navigate them.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to strengthen the link between process capability and commercial positioning. Investing in purification consistency, analytical control, and production flexibility can unlock access to higher-value applications where specification reliability is a gating factor. At the same time, building a clear regulatory and sourcing strategy helps reduce exposure to input volatility and trade-related disruption. Producers that can articulate a dependable supply narrative and back it with operational discipline are more likely to secure long-term relationships in applications where downtime or variability carries significant downstream cost.
For investors, the most relevant question is not simply whether the market is growing, but where value is concentrating and why. Growth is increasingly tied to segments with higher specification demands and to suppliers that can combine scale with reliability and compliance readiness. Evaluating potential opportunities therefore requires looking beyond headline volume and examining the quality of customer relationships, the durability of cost structures, and the ability to adapt to regulatory and supply chain shifts. Companies with diversified application exposure and clear technical differentiation are more likely to sustain competitive advantage than those dependent on a single cost-sensitive channel.
For procurement and sourcing leaders, the strategic imperative is to balance cost efficiency with resilience in a market where concentration and volatility raise the stakes of supply disruption. Diversifying supplier relationships, understanding the regulatory posture of each source, and securing visibility into capacity and contingency plans can reduce risk without abandoning cost discipline. In practice, this means treating supplier selection as a multi-dimensional decision that includes technical fit, delivery reliability, compliance transparency, and the ability to support changing demand patterns over time.
As the market continues to evolve, the availability of detailed, segment-level intelligence becomes a critical input to decision-making. Granular visibility into application dynamics, regional demand shifts, purity-grade movement, and supplier-specific strategies can clarify where competitive advantage is being created and where exposure is accumulating. For teams responsible for planning, sourcing, or investment allocation, access to comprehensive and regularly updated analysis can reduce uncertainty and improve the quality of strategic choices. PW Consulting's full research report on the Isophthalonitrile market provides a more detailed breakdown of these dynamics, including deeper segmentation, competitive profiling, and scenario-based guidance for navigating the next phase of market development.
Polyacrylonitrile (PAN) Market
For detailed analysis of this topic, please visit the official page: Isophthalonitrile (INP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thermal Barrier Coatings Market: Why a 5.1% CAGR Redefines Strategic Entry
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Thermal Barrier Coatings (TBC) Market: A 2025 Executive Brief
The thermal barrier coatings market has matured into a critical enabler of industrial efficiency and emissions compliance across multiple heavy-industry verticals. As of 2025, the global market has crossed the $18.1 billion threshold, building on a consistent growth trajectory from the 2020 baseline of approximately $13.5 billion. The sector is projected to sustain a compound annual growth rate of 5.1% through the 2032 horizon, reaching roughly $25.3 billion by the end of the forecast period. This expansion is not merely cyclical; it reflects structural shifts driven by regulatory tightening, operational cost pressures, and incremental breakthroughs in coating architecture and application methods.
For decision-makers operating in manufacturing, energy, aerospace, or capital equipment supply chains, the TBC landscape presents both defensive and offensive opportunities. Below is a strategic assessment of market realities, core drivers, competitive positioning, forward-looking trends, and actionable implications.
Market Snapshot and Core Challenges
A Market at an Inflection Point
The segment has moved past the post-pandemic recovery phase. After crossing the $15.6 billion mark in 2023, the market accelerated noticeably in 2024 and 2025, reflecting renewed industrial capex, expanded turbine fleets, and higher adoption rates in downstream applications. The forecast arc through 2032 suggests compounding gains, though the growth profile is uneven across disciplines and value chains. Sustained momentum will depend on whether manufacturers can address persistent input cost pressures, integrate higher-performance material architectures, and navigate a regulatory environment that simultaneously pushes adoption and constrains certain production pathways.
SiC and TaC Coated Graphite Market
Constraint One: High Input Costs and Material Economics
The procurement cost of advanced coating inputs remains a structural headwind. High-purity ceramic compounds and specialized mixed-metal alloys carry significant production complexity, and their price sensitivity is amplified in regions where raw material supply chains are fragmented. For operators running high-volume thermal spray lines, raw material expenditure directly compresses margins unless offset by yield improvements, process automation, or premium product positioning. This cost pressure is particularly acute for mid-tier applicators that lack scale advantages in powder procurement or process repeatability.
Constraint Two: Environmental Compliance in Manufacturing
Regulatory expectations extend beyond end-use performance to the manufacturing process itself. Certain coating production routes generate hazardous waste streams that require controlled disposal and compliance management. As environmental oversight tightens, firms must invest in containment, waste minimization, and process redesign. This adds a layer of operational complexity and cost that can delay expansion plans for smaller service providers and increase the barrier to entry for new capacity additions.
Constraint Three: Customer Adoption Under Cost and Qualification Scrutiny
Demand-side adoption is ultimately gated by return-on-investment calculations. Industrial operators weigh coating performance gains—higher inlet temperatures, extended component life, reduced cooling requirements—against upfront application cost and downtime. In sectors with long qualification cycles or conservative risk tolerance, even compelling performance data can stall procurement decisions unless supported by robust service-level commitments, repeatability evidence, and lifecycle cost modeling. The challenge is not market awareness; it is commercial proof at scale.
Key Drivers Shaping Market Trajectory
Technological Innovation and Process Maturation
Performance differentiation increasingly depends on process precision and material architecture. Advanced ceramic formulations continue to anchor the largest share of coating value, while metallic and hybrid systems provide targeted benefits in specific thermal and mechanical environments. The market is seeing greater emphasis on process controllability—particularly in plasma spray and related deposition methods—where temperature management, particle velocity, and layer uniformity determine the balance between thermal protection and mechanical durability. Improvements in line automation, particulate control, and in-line inspection are reducing variability and improving throughput, making high-performance coatings more economically viable across broader application sets.
Regulatory and Policy Momentum
Emission regulations on combustion systems are tightening globally, prompting governments and industrial regulators to introduce increasingly stringent performance norms for engines and industrial turbines. These rules incentivize technologies that improve fuel efficiency, reduce thermal stress, and extend component longevity—characteristics that TBC solutions directly support. Policy signals are further reinforced by broad industrial budgeting patterns: a meaningful share of industrial capital allocation is now directed toward energy efficiency improvements, creating a supportive backdrop for coating adoption in both new-build and retrofit scenarios. At the same time, manufacturers must manage the dual-edged nature of regulation, balancing end-use compliance benefits against the operational requirements of cleaner production practices and waste handling.
Worldwide Long-lasting Thermal Insulation and Cooling Coating Market
Demand-Side Shifts in High-Value Verticals
Demand is being reshaped by the operational priorities of aerospace, power generation, automotive, oil and gas, and industrial service providers. In aerospace, higher turbine operating temperatures and extended on-wing performance expectations continue to drive TBC utilization in engine components. In power generation, efficiency targets and cycle upgrades support coating adoption in gas turbines and related hardware. Industrial combustion and processing equipment are also seeing increased retrofit activity as operators seek to reduce fuel consumption and thermal degradation without full asset replacement. A useful market lens is the concentration of enterprise value: a relatively small group of large players accounts for a substantial share of revenue, indicating that scale, certification depth, and service breadth still matter greatly in winning major programs.
Supply Chain and Cost Structure Evolution
Supply-side dynamics are being re-shaped by regional capacity decisions, powder sourcing strategies, and service network expansion. Vertically integrated players that control powder production alongside application services are better positioned to manage input variability and co-develop formulation changes with end customers. Meanwhile, specialized powder suppliers and dedicated service shops compete on purity, availability, and certification readiness. Cost structure improvements are increasingly coming from process digitization, optimized spray parameters, and tighter quality controls rather than from broad commodity-style input deflation. As a result, competitive advantage is shifting toward firms that can combine material expertise with repeatable service delivery and regional proximity to key customer clusters.
A concrete example of this shift is visible in ongoing advanced collaboration between major thermal spray operators and engine manufacturers to integrate digital process workflows into TBC production. The move toward a smarter thermal spray factory—linking process data, quality feedback, and production scheduling—illustrates how the industry is moving from isolated application services to integrated, data-driven manufacturing models. Such arrangements aim to improve throughput, reduce rework, and enhance traceability, which is increasingly important for customers operating under rigorous qualification and maintenance regimes.
Competitive Landscape and Leading Strategies
How Leading Players Differentiate
The market is characterized by a mix of diversified surface technology providers, specialist coating applicators, and material suppliers. Several patterns define how leading firms compete:
- Vertical integration across powder and service : Companies that combine specialty powder supply with thermal spray and coating services can align material selection with application performance, reduce dependency on third-party inputs, and respond more quickly to customer formulation requirements. This model is especially valuable in aerospace and gas turbine work where material traceability and consistency are central procurement criteria.
- Process capability as a moat : Providers with advanced deposition capabilities, including controlled plasma spray and related high-precision methods, gain an edge when customers require repeatable microstructures, tightly managed porosity, and certification-ready documentation. Process maturity also supports higher-value service work such as repair, strip, and re-coat operations.
- Service network scale and certification depth : Global coverage and broad facility footprints help capture both OEM programs and MRO demand. In segments where turnaround time and regional support matter, a wide network of qualified facilities can be as important as raw coating performance.
- Industrial surface expertise across multiple end markets : Some firms compete by offering a broad service portfolio across aerospace, industrial, and regional maintenance applications. This diversification can stabilize revenue against cyclicality in a single vertical while enabling cross-learning across coating requirements.
- Application focus on civil engine maintenance : Certain players emphasize air plasma spray and high-velocity processes tailored to civil engine MRO, positioning around maintenance reliability, turnaround efficiency, and compliance with aviation standards.
- OEM-aligned service facilities : Providers with plasma spray facilities qualified by major OEMs compete on program access, repeatability, and the ability to support production and aftermarket demand under established quality frameworks.
- Regional MRO specialization : Smaller and mid-market applicators often win by offering certified TBC coating and repair services close to customer bases, serving regional maintenance demand with FAA-aligned processes and lower overhead than global networks.
- Powder and process specialization for regional demand : Specialized applicators focusing on plasma spray and high-velocity processes fill niche demand in regional MRO and industrial service, competing on agility, responsiveness, and cost-competitive service packaging.
Market Structure and Evolution Trends
The revenue concentration pattern—where a relatively small set of large players accounts for a significant share of total market value—signals that scale, certification infrastructure, and service breadth remain decisive. This does not imply a stagnant market, however. Several evolutionary dynamics are visible:
- Consolidation of high-value service capacity : Major players continue to strengthen integrated offerings that span powder supply, deposition equipment, and coating services, particularly where digital process control and smart factory capabilities can be leveraged to improve consistency and throughput.
- Segmentation between global platforms and regional specialists : While large global providers target OEM relationships and multi-region demand, regional and mid-market applicators maintain relevance by serving localized MRO needs, offering shorter lead times, and competing on service agility.
- Rising importance of process digitization : As customers demand better traceability, quality predictability, and cost control, firms that embed digital process monitoring, data feedback, and standardized operational workflows are better positioned to command premium service contracts and reduce variability.
- Material supplier positioning : High-purity ceramic powder suppliers play a critical upstream role. Their value is tied to purity, batch consistency, and the ability to support advanced coating designs. Where powder availability or quality fluctuates, downstream applicators face both cost and performance risk, making supplier relationships strategically important.
Forward-Looking Trends for the Next 3–5 Years
Trend One: Energy Efficiency as a durable Demand Anchor
Tightening combustion emissions expectations and broader industrial efficiency goals are likely to keep TBC adoption on a positive trajectory. Components that enable higher thermal operating margins, lower cooling penalties, and longer service intervals will remain attractive to operators managing fuel cost and asset utilization. Over the next several years, this should sustain demand across gas turbines, engine hardware, and industrial combustion systems, particularly where retrofit economics favor partial upgrades over full replacement. The commercial opportunity lies in packaging performance benefits with clearly modeled lifecycle savings and service commitments that reduce perceived procurement risk.
Trend Two: Process Intelligence and Quality Consistency as Value Multipliers
The market is increasingly rewarding providers that can demonstrate repeatable outcomes rather than only superior nominal coating properties. Process digitization, statistical process control, and improved inspection discipline are expected to become more central to competitive positioning. Smart factory-style integration—linking deposition parameters, quality data, and production scheduling—can reduce rework, improve yield, and strengthen customer confidence in high-stakes applications. Providers that build these capabilities will be better placed to secure long-term service agreements, expand into higher-value repair work, and differentiate against lower-cost competitors whose process variability limits premium positioning.
PW Consulting
Trend Three: Regional Capacity Realignment and Service Proximity
Demand patterns are pushing a more nuanced geography of service capacity. While global platforms continue to serve multinational OEM and industrial programs, regional MRO demand remains strong and often favors providers with local certified facilities, shorter logistics cycles, and flexible service packaging. Over the forecast window, some capacity may consolidate around major customer hubs, while regional specialists may capture growth by aligning closely with local maintenance calendars, fleet renewal schedules, and industrial upgrade cycles. Companies that balance global technical credibility with regional responsiveness are likely to gain share in mixed-demand environments.
Uncertainties to Monitor
- Raw material cost volatility and supply continuity for advanced ceramic and alloy powders could compress margins or slow expansion for cost-sensitive segments.
- Environmental compliance requirements may tighten further, increasing operational complexity for manufacturing processes that generate hazardous waste and raising the cost of compliance management.
- Qualification cycles and procurement caution in conservative customer segments can slow adoption even when technical benefits are well established.
- Competitive intensity may rise as integrated players expand service networks and regional applicators improve process discipline, compressing differentiation windows in commoditizing application segments.
Strategic Recommendations for Decision-Makers
For Coating Manufacturers and Service Providers
Strengthen the link between material capability and repeatable service delivery. Where possible, align powder sourcing, deposition process control, and inspection workflows to reduce variability and support premium service contracts. Invest in digital process monitoring and quality traceability to improve consistency, reduce rework, and strengthen qualification readiness. For regional operators, prioritize certified capacity near key maintenance clusters and develop service packages that balance turnaround speed with documentation rigor. For larger platforms, pursue selective integration—whether through advanced process partnerships, digital factory capability, or expanded regional service presence—to reinforce both performance credibility and responsiveness.
For Investors and Strategic Capital Allocators
Evaluate exposure based on value-chain positioning rather than headline market size alone. Businesses that combine material expertise, process maturity, and a credible path to cost control are better insulated from input cost pressure and better placed to capture premium MRO and OEM-linked demand. Monitor the impact of efficiency-driven capex and emissions-driven upgrade cycles on end-market demand, while tracking the risk side: regulatory compliance burdens in manufacturing, raw material volatility, and the potential for value migration toward digitally enabled service models. Diversification across verticals can stabilize returns, but differentiated process capability remains the stronger long-term differentiator.
For Procurement and Asset Operators
Treat TBC adoption as a lifecycle decision rather than a unit-cost purchase. Evaluate total cost of ownership including thermal performance gains, component life extension, maintenance downtime, and qualification support. Prioritize suppliers that can provide documented process repeatability, robust service-level commitments, and clear evidence of performance consistency across production lots. In retrofit and upgrade scenarios, quantify fuel savings, cooling reductions, and maintenance interval improvements to justify investment. Where operational risk is high, prefer partners with established certification records and regional support capacity to reduce execution risk during installation and maintenance windows.
Closing Perspective
The thermal barrier coatings market is moving from a phase of steady expansion to one where performance reliability, process intelligence, and regulatory alignment determine competitive outcomes. Growth through the early 2030s is supported by efficiency mandates, turbine and engine performance requirements, and continued industrial investment in energy-saving technologies. At the same time, margin pressure from high-cost inputs, compliance demands on manufacturing, and customer scrutiny of lifecycle value will reward operators that can deliver consistent quality, strong service networks, and credible economic justification. For executives and investors, the most valuable intelligence is not simply how large the market will become, but where differentiation is being created along the value chain and which capabilities will command premium positioning in a maturing, increasingly digitized competitive environment.
For detailed analysis of this topic, please visit the official page: Thermal Barrier Coatings (TBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Shifts and Commercial Opportunities in the First Aid Kits Market
The first aid kits market has evolved from a commodity-driven safety staple into a strategically differentiated segment where compliance, content innovation, and service models dictate competitive advantage. Valued at approximately $215.0 million in 2025 and projected to reach $284.0 million by 2032, the market reflects a compound annual growth rate of 4.2 percent over the 2026–2032 forecast period. This trajectory is not merely a function of population growth or baseline safety demand; it is being reshaped by regulatory realignment, supply chain pressures, and a structural shift toward specialized, application-specific kits. For executives, investors, and procurement leaders, the current environment presents both operational complexity and clear avenues for margin expansion if positioned correctly.
Understanding where value is created requires looking beyond headline revenue figures. The market's expansion is uneven across types and applications, with common-type kits continuing to anchor volume while special-type kits capture higher unit margins through specialized content and targeted use cases. Application-wise, industrial and commercial environments remain central demand centers, but home care and sports-related deployments are gaining relevance as safety awareness broadens beyond traditional workplaces. Regionally, mature markets continue to set compliance benchmarks, while emerging regions are expanding at a faster pace as regulatory frameworks and workplace safety cultures mature. This fragmentation is not a weakness; it is the structural basis for differentiated go-to-market strategies.
Market Snapshot and Structural Realities
The growth path from 2020 through 2025 demonstrates steady accumulation, with revenue moving from $163.15 million to $215.0 million. The forecast window extends that momentum, reaching $227.94 million in 2026 and climbing toward $284.0 million by 2032. While the overall CAGR of 4.2 percent suggests a mature, predictable market, the underlying pattern reveals inflection points. Growth is not linear; it is being accelerated in segments where regulatory mandates, specialized content, and managed replenishment models intersect. This is why the market's midpoint values matter less than the rate of change within specific applications and kit types.
The industry structure also reflects a moderate degree of concentration. The top three players account for roughly 42.5 percent of market share, while the top five reach approximately 58.7 percent. This concentration indicates that scale, distribution reach, and compliance expertise provide meaningful defensive moats. At the same time, the remaining share distribution leaves room for specialized entrants, private-label partners, and service-led models to compete on differentiation rather than price alone. For decision-makers, the implication is clear: the market rewards players who can align product content, regulatory readiness, and replenishment reliability rather than those who compete purely on kit count or unit cost.
Key Challenges and Inflection Points
The first aid kits market is navigating a set of interdependent challenges that will determine which players gain share and which are squeezed into low-margin commoditization. These challenges are not transient; they are structural and require strategic responses.
- Regulatory and standards realignment is raising the compliance floor. Recent revisions to first-aid kit specifications and quality management expectations are reshaping what qualifies as an acceptable kit in workplace and industrial settings. Compliance is shifting from a static checkmark to an ongoing operational requirement, increasing the importance of documentation, content consistency, and manufacturing discipline.
- Input cost volatility is compressing margins for undifferentiated products. Prices for medical-grade gloves, antiseptic consumables, and trauma care materials rose by nearly 18 percent between 2023 and 2025, driven by supply concentration in Asia and elevated freight costs. Manufacturers and distributors that rely on generic content structures or reactive sourcing are facing margin pressure that cannot be fully passed through to price-sensitive buyers.
- Demand fragmentation is making one-size-fits-all kits less defensible. Buyers increasingly expect kits aligned to specific risk profiles, occupancy types, and operational environments. The broad-volume play is losing differentiation value, while application-tailored kits, replenishment services, and rental or managed stock models are gaining relevance.
Together, these dynamics create a market where compliance readiness, content precision, and service integration are becoming the primary levers of competitive advantage. Companies that treat first aid kits as a simple resell or assembly business will face intensifying pressure, while those that embed quality systems, tailored content, and replenishment reliability into their offering will be better positioned to defend pricing and expand share.
Key Drivers Reshaping the First Aid Kits Market
The market's direction is being shaped by four interlocking drivers: regulatory and standards evolution, input cost and supply chain dynamics, demand-side behavior changes, and product and service innovation. Each driver influences not only volume but also the economics of competition.
Regulatory and Standards Evolution as a Structural Driver
Regulatory developments are no longer peripheral; they are actively redefining product eligibility and manufacturing expectations. The Quality Management System Regulation (QMSR) became effective in February 2026, aligning FDA CGMP requirements with ISO 13485:2016 for medical devices, including first aid kits. This shift matters because it connects first aid kit production more directly to internationally recognized quality management expectations. For manufacturers, the change raises the importance of documented processes, traceability, and consistent quality control. For buyers, it increases confidence in supplier reliability but also raises the bar for supplier qualification.
At the same time, state-level standards activity is pushing kit specifications toward more defined performance expectations. Recent proposals to revise first-aid kit requirements in California have pointed toward alignment with ANSI/ISEA Z308.1-2021 Class A specifications for 2026 compliance. Even where such revisions are still evolving, they signal a broader direction: kit content is being evaluated against more explicit benchmarks rather than generic notions of adequacy. This creates a dual effect. It rewards manufacturers that can demonstrate specification alignment and documented quality systems, while increasing the cost of remaining in the low-compliance segment.
Worldwide Antiseptic First Aid Liquid Market
For commercial strategy, the regulatory driver is best understood as a filter. It does not automatically expand the market, but it accelerates consolidation among suppliers that can meet higher compliance expectations and squeezes out marginal players that cannot sustain the required documentation and process discipline.
Input Cost Dynamics and Supply Chain Realities
Cost structure is becoming a strategic variable rather than a background assumption. The nearly 18 percent increase in prices for medical-grade gloves, antiseptic consumables, and trauma care materials between 2023 and 2025 reflects a combination of supply concentration and freight pressure. This is not simply a purchasing challenge; it influences product architecture, pricing strategies, and the viability of low-differentiation kits.
The most exposed players are those with limited sourcing flexibility and minimal content optimization. When input prices rise, the temptation is to pass costs downstream, but in price-sensitive segments that approach can erode demand or trigger substitution. More resilient players are managing the pressure through a combination of supplier diversification, content rationalization, and value-based packaging. In practice, this means rethinking what goes into a kit, how consumables are replenished, and whether certain items can be sourced or configured in ways that reduce volatility without compromising compliance or functionality.
Supply chain concentration also increases the strategic value of inventory planning and replenishment design. Kits that depend on fragile sourcing paths are vulnerable not only to cost shocks but also to availability disruptions. This is one reason managed replenishment, rental systems, and private-label partnerships are gaining attention: they shift part of the burden of continuity from the end buyer to the supplier, creating a more predictable operating model and a stronger customer relationship.
Demand-Side Shifts in Behavior and Expectations
Demand is changing in ways that favor application specificity and service reliability. Workplace safety expectations are rising, and buyers are increasingly aware that compliance alone is not the same as operational readiness. In industrial and commercial environments, the question is no longer just whether a kit is present, but whether its content matches the actual risk profile of the site, whether it is maintained, and whether replenishment happens without delay.
Home care and sports-related applications are also contributing to broader demand diversification. These segments may not carry the same regulatory weight as industrial settings, but they are expanding the addressable market and encouraging product designs that are easier to use, easier to store, and more intuitive for non-specialist users. The common thread across these demand shifts is that buyers are paying more attention to usability, maintenance, and relevance. Kits that are difficult to restock, poorly matched to real-world use, or opaque in their replenishment process lose credibility quickly.
This demand evolution also affects purchasing behavior. In some contexts, buyers are moving from one-time purchases toward ongoing service relationships. Managed restocking, cabinet solutions, and rental or replenishment programs reduce the administrative burden on buyers and create recurring revenue streams for suppliers. The shift is incremental but meaningful because it changes the economic logic of the market from transactional volume to relationship-based continuity.
Product and Service Innovation as a Competitive Lever
Innovation in this market is less about radical product reinvention and more about precision, usability, and service integration. Special-type kits illustrate this trend by targeting specific scenarios with content designed for higher-acuity needs. Trauma-oriented kits, bleeding control kits, and other specialized configurations are gaining attention because they address use cases where generic kits are insufficient. This does not replace the role of common-type kits, but it creates a higher-value layer in the market where differentiation is easier to sustain.
PW Consulting Health Care Research Center
Service models are also evolving. Wholesale distribution, private-label and contract manufacturing, and managed rental or restocking systems reflect a broader move toward integrated offerings. These models matter because they address multiple buyer pain points at once: compliance, content relevance, replenishment reliability, and administrative burden. Where successful, they create stickier customer relationships and more predictable revenue than standalone kit sales.
Innovation is also visible in how suppliers position themselves for different buyer types. Some players emphasize cost-effective OSHA-compliant workplace kits and refills, which appeal to buyers focused on baseline compliance and operational efficiency. Others prioritize ANSI/OSHA-compliant workplace, industrial, and construction kits, signaling a more specification-driven approach. A further group concentrates on trauma and public-access bleeding control kits, targeting higher-risk environments and first-response needs. Another set of suppliers focuses on premium kits selected by first responders and medical professionals, using clinical credibility as a differentiator. Taken together, these positions show that the market is no longer competing on a single value proposition; it is fragmenting into multiple value pools, each with its own buyer expectations and pricing logic.
Competitive Landscape and Winning Strategies
The competitive field is marked by a mix of scale players, compliance-focused suppliers, specialized trauma-oriented providers, and service-oriented distributors. The presence of established names alongside niche specialists suggests a market where different competitive models can coexist, but only if each is clearly aligned to a defensible position.
Strategic Positioning Among Leading Players
A closer look at leading players shows that competitive advantage is being built through distinct positioning rather than uniform product offerings.
- First Aid Only has leaned into cost-effective, OSHA-compliant workplace kits and refills. This positions the company around baseline compliance, operational simplicity, and replenishment continuity for workplace environments. The strategic value lies in serving buyers who need dependable, specification-aligned kits without unnecessary complexity.
- The American Red Cross emphasizes ANSI/OSHA-compliant workplace, industrial, and construction kits. Its positioning benefits from institutional credibility and a strong association with safety and preparedness. In markets where trust and recognized authority matter, this is a meaningful advantage.
- North American Rescue focuses on trauma and first aid kits, including lumbar first aid kits and public access bleeding control kits. This places the company in a higher-specialization segment where content precision and mission-relevant design can support premium positioning.
- Aero Healthcare operates across wholesale kits, private-label and contract manufacturing, and managed rental or restocking systems. This multi-track model is strategically important because it combines distribution reach with service-based revenue and custom branding opportunities.
- My Medic emphasizes premium first aid kits and supplies selected by first responders and medical professionals. Its differentiation rests on clinical credibility and curated content, appealing to buyers who value expert selection and higher-performance configurations.
- Cintas Corporation offers first aid kits, cabinets, and replenishment services for workplace use. The strength of this model is integration: by combining hardware, kits, and replenishment, it reduces fragmentation for buyers and creates recurring service relationships.
- JumpMedic concentrates on premium first aid kits and supplies designed for emergency needs. Its positioning targets urgent-use scenarios where readiness, usability, and content reliability are especially important.
The pattern across these players is not random. Each is pursuing a distinct value pool: compliance and efficiency, institutional trust, trauma specialization, service integration, clinical credibility, or emergency readiness. The market supports multiple models because buyer needs differ by environment, risk profile, and procurement style. What separates stronger performers from weaker ones is the ability to deliver consistently on the chosen position without diluting it through unrelated expansion.
How the Landscape Is Evolving
The competitive landscape is evolving along three axes: consolidation among scaled players, differentiation among specialists, and new entry through service-led and private-label models.
Consolidation remains plausible where scale, distribution reach, and compliance infrastructure create advantages in procurement, qualification, and ongoing account management. In a market where the top five players already account for a majority share, further consolidation would likely be driven by the need to strengthen replenishment networks, broaden application coverage, and absorb regulatory and quality-system requirements more efficiently.
At the same time, differentiation is intensifying among specialists. Trauma kits, bleeding control kits, premium responder-selected kits, and application-specific configurations are creating spaces where performance and credibility matter more than sheer volume. These segments are smaller in absolute terms but can support stronger margins and more loyal customer bases when executed well.
New entry is also emerging through service-oriented models and private-label partnerships. Buyers that want compliance, replenishment, and brand alignment without building internal complexity are natural candidates for rental, restocking, and contract manufacturing arrangements. This creates opportunities for suppliers that can combine operational reliability with flexible commercial terms, even if they do not lead in raw brand recognition.
The overall trend is toward a market where success depends less on being everywhere and more on being unambiguously strong in a chosen segment. Players that attempt to compete across all applications, all kit types, and all service models without clear prioritization risk being outflanked by more focused competitors.
Forward Outlook: Three Trends to Watch Over the Next 3–5 Years
Looking ahead, the market is likely to be shaped by the interaction of compliance, cost, and demand specificity. Three trends are especially relevant for strategic planning.
Trend 1: Compliance and Quality Systems Will Become Table Stakes, Not Differentiators Alone
As quality management expectations align more closely with recognized international standards and kit specifications continue to be refined, the baseline for market participation will rise. This does not automatically create growth, but it does change the competitive filter. Suppliers that can demonstrate consistent quality, documentation discipline, and specification alignment will face lower qualification friction and stronger buyer confidence. Those that cannot will find it increasingly difficult to remain viable in regulated workplace and industrial channels. The commercial implication is that compliance capability should be treated as core infrastructure, while differentiation will need to come from content relevance, service design, and segment focus.
Worldwide Home Safety Test Kits Market
Trend 2: Application-Tailored Kits and Managed Replenishment Will Capture More Value
Demand is moving toward kits that match real-world risk profiles and toward purchasing models that reduce maintenance burden. This favors suppliers that can design for specific environments, maintain stock reliability, and offer replenishment, rental, or cabinet-plus-service solutions. The opportunity is not only in selling more kits, but in shifting the relationship from transactional purchase to ongoing readiness. For manufacturers and distributors, this trend opens a path to recurring revenue and stronger account retention, provided the operational backbone can support reliable restocking and service execution.
Trend 3: Cost and Sourcing Strategy Will Separate Resilient Players from Marginal Ones
Input cost pressure is unlikely to disappear quickly, especially where supply concentration and freight exposure remain factors. The strategic response will matter more than the headline cost itself. Players that diversify sourcing, optimize content without sacrificing compliance, and build replenishment models that smooth volatility will be better positioned to protect margins. Those that rely on rigid supply paths or undifferentiated kit architectures will be more exposed to price competition and availability risk. Over the next few years, sourcing resilience and content architecture will increasingly determine who can sustain pricing power.
Risks and Uncertainties
These trends are directionally clear, but several uncertainties could alter the pace or shape of market development. Regulatory specifications may evolve unevenly across regions, creating compliance complexity for suppliers operating in multiple jurisdictions. Input cost volatility could intensify if supply concentration persists or if logistics costs rise again. Demand may also shift faster than expected in certain applications, particularly where safety awareness grows or where workplace and public-access preparedness requirements become more stringent. Finally, competitive intensity could increase if new entrants successfully use private-label, rental, or replenishment models to bypass traditional distribution barriers. Each of these risks can be managed, but only if they are anticipated rather than treated as external shocks.
Strategic Actions for Decision-Makers
The first aid kits market rewards clarity of position, operational discipline, and readiness to align product content with real-world use. The following actions are most relevant for different audience types.
For Manufacturers and Brand Owners
- Strengthen quality management and specification alignment as a foundation, not a side initiative. With regulatory expectations moving toward more formalized quality frameworks, the ability to document processes and demonstrate consistent compliance is becoming a market-access requirement.
- Reassess kit content architecture against input cost realities. Where possible, optimize consumables, diversify sourcing, and differentiate through application-specific configurations rather than relying on generic volume plays.
- Choose a defensible value pool and execute against it. Whether the focus is workplace compliance, trauma specialization, responder-selected premium kits, or service-led replenishment, clarity of positioning will matter more than broad but shallow coverage.
For Investors and Strategic Buyers
- Evaluate exposure to compliance-dependent channels and service-based revenue. Businesses with recurring replenishment, rental, or managed stock models may offer more predictable economics than pure transactional kit sales, especially if they can demonstrate reliable execution.
- Look for sourcing and content strategies that signal resilience. Suppliers with diversified supply paths, disciplined cost management, and clear segment focus are better positioned to withstand input price volatility and competitive pressure.
- Assess whether a target's differentiation is real or aspirational. In this market, credibility in specific applications and the ability to maintain specification alignment over time are stronger signals than broad brand claims.
For Procurement and Safety Leaders
- Shift evaluation criteria beyond unit price to include replenishment reliability, compliance documentation, and content relevance. The total cost of an inadequate or poorly maintained kit can exceed the apparent savings from a cheaper purchase.
- Align kit selection to actual site risk profiles and usage patterns. Over-specified kits can waste resources, while under-specified kits can create readiness gaps; the goal is fit, not maximum content.
- Consider service models where administrative burden and restocking risk are significant. Managed replenishment, cabinets, and rental or contract arrangements can improve continuity if the provider demonstrates reliable execution and clear compliance support.
The first aid kits market is entering a phase where strategy matters more than scale alone. Compliance expectations are rising, input costs are reshaping margins, and buyers are increasingly focused on readiness, relevance, and continuity. In that environment, the winners are likely to be those who combine quality discipline with clear segmentation, reliable replenishment, and content designed for real-world use. For organizations seeking a more detailed view of segment dynamics, regional variation, and tailored commercial options, a comprehensive research report can provide the deeper segmentation and scenario detail needed to translate these strategic signals into actionable plans.
For detailed analysis of this topic, please visit the official page: First Aid Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aseptic Packaging Market: Why 10.5% CAGR and 156 Billion Scale Redefine Growth
By PW Consulting, 2026-09-21
Aseptic Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
The global aseptic packaging sector has cemented its status as a critical infrastructure layer across food, beverage, and pharmaceutical value chains. Between 2020 and 2025, the market expanded from approximately $45.7 billion to $78.3 billion, reflecting sustained demand for shelf-stable, contamination-resistant containment solutions. Forward-looking estimates project the market to surpass $156 billion by 2032, underpinned by a compound annual growth rate of 10.5 percent. This trajectory signals more than incremental growth; it reflects a structural reconfiguration of how liquids and sensitive goods are preserved, distributed, and consumed across geographies.
Yet the figures only sketch the surface. Beneath the headline expansion lies a sector navigating material science transitions, regulatory realignments, and shifting distribution economics. Decision-makers who treat aseptic packaging as a static commodity risk missing both margin compression and strategic positioning opportunities. Understanding the forces reshaping the market is essential for aligning capital allocation, product development, and supply chain strategy with the next phase of industry evolution.
Market Snapshot and Core Challenges
The aseptic packaging market operates at the intersection of food safety, pharmaceutical integrity, and logistical efficiency. Cartons and bags/pouches collectively represent the dominant format categories, while food and beverage applications account for the majority of end-use demand. Regional demand is distributed across developed and emerging markets, with Asia Pacific and North America capturing substantial share, supported by mature dairy and juice ecosystems as well as expanding ready-to-drink and nutritional supplement segments.
Despite robust top-line growth, the industry is approaching several inflection points that warrant strategic attention.
Material Compliance and Recyclability Pressures
Regulators and brand owners are increasingly treating end-of-life performance as a design constraint rather than an afterthought. The EU Packaging and Packaging Waste Regulation entered into force in February 2025 and establishes recyclability requirements for packaging placed on the European market, with detailed design-for-recycling criteria expected to be finalized through delegated acts by 2028. For aseptic packaging specifically, compliance pathways are pushing manufacturers toward aluminum layer minimization and mono-material component architectures. This shifts the competitive basis from mere barrier performance to total recyclability yield and compliance documentation.
Material Substitution and Barrier Technology Race
Traditional aseptic structures have long relied on multi-layer laminates incorporating aluminum foil to achieve microbial barrier and extended shelf life. The push toward recyclable mono-material systems is intensifying investment in paper-based barriers, polymer alternatives, and advanced sealing technologies. Companies pioneering aluminum-free or low-aluminum solutions are betting that recyclability, brand owner ESG commitments, and potential extended producer responsibility cost structures will reward early movers. However, the technical challenge remains substantial: maintaining sterility, oxygen and light barrier properties, and seal integrity without compromising recyclability.
Capacity Realignment and Regional Demand Divergence
Investment patterns indicate a deliberate expansion of aseptic carton and filling capacity in markets serving dairy, shelf-stable beverages, and emerging consumer categories. Simultaneously, pharmaceutical-grade vial, ampoule, and sterile transit packaging demand is being shaped by biologics growth, cold-chain complexity, and regulatory scrutiny. The divergence between high-volume food-grade aseptic systems and precision pharma packaging creates different capital intensity profiles, lead-time expectations, and quality assurance requirements, complicating one-size-fits-all capacity planning.
Key Drivers Shaping Market Trajectory
Several interlocking forces explain why the market is advancing at a double-digit growth cadence while simultaneously restructuring around compliance and material innovation.
Technological Innovation in Barrier and Filling Systems
The most consequential technical shift is the transition from conventional aluminum-dependent aseptic structures to recyclable mono-material and aluminum-minimized designs. Tetra Pak’s EUR 60 million investment in a new pilot plant in Lund, Sweden, focused on paper-based barrier technology to replace aluminum foil in aseptic cartons illustrates how incumbents are reallocating R&D toward recyclable architectures. SIG has similarly rolled out aluminum-free aseptic carton solutions in select European markets, targeting improved recycling yield for dairy and juice applications. On the equipment side, aseptic filler and bottling line providers are refining PET and flexible format lines to handle new material specifications without sacrificing throughput or sterility assurance. The implication is clear: aseptic packaging is becoming a materials-and-engineering problem as much as a containment problem, and differentiation will increasingly derive from demonstrable recyclability, performance consistency, and line compatibility.
Regulatory Environment Reshaping Design and Sourcing
Regulatory momentum is no longer confined to safety and labeling; it now directly influences structural design and procurement strategies. The EU PPWR’s phased application timeline creates a near-term compliance window that favors firms able to redesign structures, validate recycling streams, and document design-for-recycling criteria ahead of delegated act finalization. For multinational manufacturers and brand owners, this regulatory environment introduces both cost and opportunity: early alignment can reduce future redesign fatigue, mitigate potential compliance penalties, and strengthen sustainability claims in markets where packaging performance is scrutinized by retailers and consumers alike. Conversely, lagging players may face restructuring costs, stranded assets in non-compliant formats, and slower market access in regulated regions.
Sterile Medical Packaging Market
Demand-Side Evolution in Food and Beverage
Consumer and retail behavior continues to reinforce demand for shelf-stable, portable, and clean-label compatible packaging. Aseptic cartons and pouches remain attractive for dairy, juices, plant-based beverages, and liquid foods because they combine protection with supply chain flexibility. Recent product category expansions, such as SIG’s entry into camel milk with new aseptic carton solutions, highlight how format adaptability enables penetration into niche and regional dairy segments that demand both sterility and cultural product specificity. Beyond traditional categories, the broader trend toward functional beverages, premium juices, and ready-to-consume nutrition products is expanding the addressable space for aseptic systems that can preserve product quality without preservatives or continuous refrigeration.
Supply Chain and Cost Structure Realignment
Aseptic packaging economics are being reshaped by raw material dynamics, regionalized production, and the cost of compliance. The emergence of large-scale carton manufacturers in Asia, including publicly listed players now ranking among the world’s largest aseptic carton producers, adds scale competition and regional sourcing alternatives. At the same time, investments in Mexico and other nearshore locations, such as SIG’s additional US$ 35 million expansion of its Querétaro aseptic carton plant, reflect a strategic emphasis on serving regional demand with localized capacity, shorter logistics routes, and tariff or trade-flow optimization. For converters and brand owners, the result is a more distributed supply base that can improve resilience but also requires tighter quality governance, specification alignment, and vendor qualification discipline.
Competitive Landscape and Leadership Strategies
The competitive field is shaped by a mix of global incumbents with integrated packaging and filling capabilities, specialized format providers, and equipment manufacturers whose technology choices influence downstream material adoption. Market concentration remains moderate, with the top three firms holding a substantial share and the top five collectively representing just over forty percent of the market. This structure suggests room for both differentiated positioning and consolidation, particularly where scale, regional presence, and technology licensing create advantages.
Differentiated Positioning Among Leading Players
Several strategic archetypes are visible across the leadership group. One focuses on integrated aseptic systems spanning carton formation, filling, and downstream support, with strong positions in dairy and liquid foods. Another emphasizes extended shelf-life plastic bottles and specialized barrier features, including UV protection and longer durability windows for specific beverage applications. A third centers on flexible bag-in-box and spouted bulk systems tailored for industrial and liquid handling use cases. A fourth stream involves sterilized transit packaging and pharma-oriented solutions, where the value proposition rests on contamination control, regulatory alignment, and handling precision rather than mass-market retail volume. Equipment specialists further shape the ecosystem by determining which packaging formats can be manufactured efficiently at scale, effectively acting as adoption accelerators for new materials and structures.
Strategic Moves and Recent Developments
Recent activity underscores how companies are translating strategy into capacity and product decisions. Tetra Pak’s Lund pilot plant investment targets paper-based barrier replacement for aluminum foil, an explicit bet on recyclable carton architecture. SIG’s aluminum-free aseptic carton rollout in Europe and its camel milk category entry show simultaneous focus on structural compliance and category diversification. SIG’s Querétaro expansion reflects a regional capacity build to support dairy and shelf-stable beverage demand closer to end markets. On the exhibition and ecosystem side, companies such as ASEPTO and Steriline have showcased aseptic liquid packaging innovations and advanced filling lines at major industry events, signaling continued emphasis on technology visibility, customer engagement, and solution-level selling. These moves collectively indicate that leadership is increasingly defined by the ability to combine material innovation, regional capacity alignment, and application-specific portfolio breadth.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve along two concurrent paths. In mature format segments, scale advantages, integrated service models, and compliance readiness may encourage consolidation or strategic partnerships, particularly where recyclability mandates increase the cost of lagging behind. In parallel, specialized niches and emerging regions may see continued fragmentation, with new entrants targeting specific applications, local material supply chains, or cost-competitive manufacturing models. The presence of large Asian carton producers and regional capacity investments suggests that price competition and localized service will matter alongside technology leadership. For customers, this means the supplier base is becoming more varied in terms of risk-return profiles, and procurement strategies will need to balance scale, compliance assurance, and regional responsiveness rather than defaulting to a single incumbent.
Future Outlook: Three Trends to Watch
Looking toward 2027 and beyond, the market appears headed toward a period in which recyclability, material substitution, and regional capacity alignment become central to commercial performance. Three trends are especially salient.
Bulk Aseptic Packaging Market
Trend 1: Recyclability-Driven Format Redesign Becomes Commercial Mainstream
As delegated design-for-recycling criteria crystallize and brand owners face mounting expectations from retailers, consumers, and regulators, recyclable mono-material and aluminum-minimized aseptic structures are likely to move from pilot and select-market usage to broader commercial deployment. This trend creates opportunities for providers that can prove equivalent barrier performance, reliable seal integrity, and compatible recycling streams. It also introduces risk for formats that cannot meet recyclability thresholds without significant redesign or process changes. Companies that establish validated recycling pathways and transparent compliance documentation will be better positioned to secure long-term brand owner contracts, particularly in Europe and other regulated markets.
Trend 2: Regionalized Capacity and Category-Specific Portfolio Expansion
Investments in localized production and category-focused solutions are expected to continue as firms seek to reduce logistics exposure, serve emerging dairy and beverage segments, and respond to trade and tariff dynamics. This regionalization will likely coincide with more targeted product development, such as carton solutions tailored to specialty milks, plant-based beverages, and nutrition liquids. The commercial opportunity lies in pairing capacity proximity with format flexibility, enabling faster response to regional demand shifts. The uncertainty is whether regional capacity builds will generate sufficient scale to offset higher unit costs in smaller markets, or whether demand concentration will remain uneven across geographies.
Trend 3: Integration of Equipment, Materials, and Service as a Competitive Moat
As material specifications become more complex and regulatory expectations rise, the ability to offer compatible filling equipment, technical support, and compliance assistance will matter more than ever. Equipment providers and packaging suppliers that coordinate material behavior with line performance, sterility assurance, and changeover efficiency can reduce customer adoption friction for new formats. This creates a strategic path for incumbents and enables differentiated service models. One risk is that integration complexity may raise barriers for smaller customers, potentially slowing diffusion of advanced recyclable formats in price-sensitive segments unless financing, training, and transition support evolve alongside the technology.
Strategic Guidance for Decision-Makers
For manufacturers, brand owners, and investors, the current environment rewards proactive positioning across material strategy, regional capacity planning, and supplier selection.
-
Manufacturers and converters should prioritize recyclable structure readiness before regulatory deadlines tighten. Investing in material testing, recycling stream validation, and design-for-recycling documentation can reduce future redesign costs and improve negotiating leverage with brand owners. Where aluminum replacement is technically feasible, piloting should be paired with line compatibility checks to ensure that new substrates perform reliably on existing filling equipment.
-
Brand owners and procurement leaders should treat supplier evaluation as a compliance-and-performance decision, not just a cost decision. Criteria should include recyclability pathway clarity, regional capacity proximity, quality assurance discipline, and ability to support format transitions. Diversifying the supplier base across scale incumbents, regional producers, and specialized format providers can improve resilience while preserving access to advanced solutions.
PW Consulting -
Investors and strategic planners should focus on companies demonstrating coordinated moves across materials, capacity, and application breadth. The strongest positioning is likely to belong to firms that can combine recyclable format leadership with regional production alignment and supportive equipment or service ecosystems. Monitoring capacity announcements, pilot plant outcomes, and regulatory milestone progress will provide early signals of which players are converting innovation into commercially scalable advantage.
The aseptic packaging market is entering a phase where growth and restructuring occur simultaneously. Demand expansion provides a favorable backdrop, but the real strategic value will be captured by those who anticipate material compliance requirements, align capacity with regional demand realities, and select partners capable of delivering both performance and transition support. Detailed segmentation data, regional nuances, and tailored scenario planning can sharpen these choices further for organizations preparing investments or portfolio decisions.
For detailed analysis of this topic, please visit the official page: Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LTCC Ceramic Substrates Market: 6.3% CAGR Trajectory and Regional Shifts to 2032
By PW Consulting, 2026-09-21
Navigating the LTCC Ceramic Substrates Market: Strategic Trends and Commercial Opportunities Through 2032
The low-temperature co-fired ceramic (LTCC) substrates market has entered a decisive growth phase, driven by the convergence of high-frequency connectivity, automotive electrification, and advanced packaging demands. Between 2020 and 2025, global revenue expanded from approximately 1,022.6 million USD to 1,458.2 million USD, reflecting sustained investment in miniaturized, high-reliability interconnect solutions. The forward trajectory points to a compound annual growth rate of 6.3 percent, with the market projected to reach 2,230.8 million USD by 2032. This expansion is not uniform; it is concentrated among a handful of established manufacturers, with the top three players capturing roughly 65 percent of revenue and the top five accounting for approximately 75 percent. The market structure signals both maturity and opportunity: incumbents hold significant technical and capacity advantages, while lingering pockets of regional and application-specific demand create room for targeted differentiation and strategic entry.
Understanding this landscape requires moving beyond aggregate numbers. The pace of growth, the concentration of supply, and the shifting priorities of end-use industries all carry direct implications for procurement planning, capacity investment, and competitive positioning. The following analysis distills the structural forces shaping the LTCC substrate market, the competitive behaviors defining the leading cohort, and the strategic choices that decision-makers should prioritize as the market moves through 2026 and beyond.
Market Landscape and Core Challenges
The LTCC substrate market has navigated a period of steady expansion, but the current environment is defined less by raw growth and more by the quality and direction of that growth. Over the past five years, demand have been supported by the adoption of multilayer ceramic architectures in applications requiring high integration density, stable dielectric performance, and robust thermal characteristics. The market's ability to grow at a mid-single-digit pace through 2032 suggests that LTCC substrates are becoming an embedded component in several technology roadmaps rather than a cyclical beneficiary of a single end market.
Despite this favorable trajectory, the industry faces three interconnected challenges that will shape competitive outcomes in the near term:
-
Demand diversification across applications and regions. Revenue is increasingly distributed among multiple application categories, with consumer electronics representing the largest segment, followed by automotive electronics, aerospace and military use, and a smaller residual category. This dispersion means that no single application can be treated as a universal proxy for market health. Suppliers must manage distinct qualification cycles, performance requirements, and volume profiles simultaneously, which complicates capacity planning and margin management.
-
Market concentration and the risk of complacency. With the top three and top five firms holding significant revenue shares, the market exhibits characteristics of a consolidated value chain. Concentration can yield scale efficiencies and consistent quality, but it also raises the bar for differentiation. Incumbents must continuously invest in material formulations, process control, and integration capabilities to defend positions, while smaller players must identify niches where specialized performance, lead-time advantages, or regional proximity offer defensible value.
-
Technology and qualification pressures in high-reliability segments. As LTCC substrates expand into automotive radar, 5G RF modules, and advanced semiconductor packaging, the tolerance for variability narrows. Meeting automotive and defense-grade expectations requires rigorous process consistency, advanced dielectric control, and documented supply-chain traceability. These requirements lengthen time-to-revenue for new designs and increase the cost of quality, pressuring firms to balance innovation with certified repeatability.
A secondary but material consideration is the stability of the input environment. Alumina feedstock prices have remained stable, with no reported increases or disruptions affecting LTCC production in 2025 and 2026. The broader alumina supply chain showed no force majeure events or capacity constraints as of early 2026, and there have been no new export controls or tariffs specifically targeting alumina or LTCC ceramic substrates in major economies during this period. Compliance with ISO 9001 and automotive AEC-Q200 standards continues as a baseline requirement without recent regulatory changes, and no new environmental restrictions or transport surcharges on key precursors have been reported. This relative calm in raw material and regulatory conditions provides a stable backdrop for investment, but it also means that competitive advantage will be determined more by process know-how and product architecture than by input cost arbitrage.
PW Consulting
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Advancements
The most compelling driver of market evolution is the ongoing refinement of LTCC materials and multilayer architectures. LTCC technology enables high-density interconnect with embedded passive elements, controlled impedance, and thermal performance suited to demanding RF and power applications. Recent product activity illustrates how manufacturers are translating material science into commercial advantage. In April 2026, a major ceramics supplier announced the commercialization of a breakthrough multilayer ceramic core substrate for advanced AI semiconductors, featuring high rigidity and circuit miniaturization, with an unveiling planned at ECTC 2026. This development signals a deliberate push to extend LTCC beyond traditional RF and sensor applications into advanced packaging domains where dimensional stability and mechanical robustness are critical.
Simultaneously, peers have focused on expanding the performance envelope for connectivity and mobility. In May 2025, a leading manufacturer introduced a next-generation ceramic substrate optimized for high-frequency 5G modules and automotive radar applications. This launch reflects the broader requirement to support wider bandwidths, tighter integration, and consistent signal integrity in environments where electrical performance and mechanical reliability must coexist. Capacity decisions reinforce this direction: in July 2025, another major player expanded production capacity for multilayer ceramic capacitors integral to LTCC substrate performance to meet automotive and telecommunications demand. These moves indicate that substrate suppliers are not only improving individual product attributes but are also aligning capacity and component availability to support system-level integration.
Ceramic Substrate Market
Policy and Regulatory Environment
The policy backdrop has been a stabilizing force rather than a disruptive one. The absence of new export controls or targeted tariffs on alumina or LTCC ceramic substrates in 2025 and 2026 has reduced the likelihood of sudden cost shocks or supply fragmentation. Equally important, the regulatory expectations that do exist—such as ISO 9001 and automotive AEC-Q200 compliance—are well established and continuously applied across active producers. For decision-makers, this means that qualification frameworks are predictable, but they still represent meaningful barriers. Firms that have matured their quality systems and documentation processes are better positioned to win automotive and defense-related programs, while newer entrants face a steeper path to certification. The policy environment therefore favors disciplined, process-oriented operators and rewards long-term investment in quality infrastructure.
Demand-Side Shifts in Consumer, Automotive, and High-Reliability Markets
On the demand side, the market is being reshaped by the needs of three broad clusters. Consumer electronics continue to provide the largest revenue base, driven by the ongoing need for compact, high-integration solutions in mobile and connectivity-oriented devices. Automotive electronics represent the second-largest segment, fueled by the expansion of advanced driver-assistance systems, radar-based sensing, and power management modules that require substrates with strong reliability profiles. Aerospace and military applications, while smaller in absolute terms, contribute disproportionately to requirements for thermal endurance, dimensional stability, and long-term consistency. The "others" category captures additional niche demands, but together these application groups highlight a market where volume and value are distributed across very different qualification and performance regimes.
This diversification matters because it changes how suppliers should allocate engineering resources. A substrate designed for high-volume consumer modules must balance cost and throughput, whereas an automotive radar substrate must prioritize repeatable RF behavior and qualification evidence. An aerospace or defense program may emphasize traceability and environmental robustness more than unit-cost optimization. The ability to serve multiple demand profiles without diluting process control is increasingly a defining capability.
Supply Chain and Cost Structure Dynamics
Cost structure dynamics have been characterized by input stability and process-driven differentiation. Stable alumina feedstock pricing and the absence of force majeure events in the global supply chain through early 2026 have kept variable cost risk contained. However, LTCC substrate economics are increasingly influenced by factors beyond raw materials: layer count, via formation precision, dielectric consistency, yield management, and integration of embedded components all affects the cost-to-performance ratio. Firms that can raise performance while maintaining yield and minimizing rework will capture margin advantages, even in a stable input environment. This is why capacity expansions are often paired with product launches and material innovation rather than treated as standalone volume plays. The market rewards integrated improvements rather than isolated scaling.
Competitive Landscape and Leading Strategies
The competitive field is dominated by a dense cluster of Japanese manufacturers, complemented by notable European, U.S., and select Asian players. This geographic concentration reflects decades of accumulated expertise in ceramic materials, multilayer processing, and high-frequency component integration. The major firms have built strong positions by aligning substrate capabilities with adjacent component businesses, such as multilayer capacitors, RF modules, and precision sensors, which allows them to serve system integration requirements more holistically.
Several strategic patterns emerge among the leaders:
-
Vertical alignment with component ecosystems. Leading manufacturers often combine LTCC substrates with complementary passive and active components. This integration supports higher-density designs and reduces the customer's need to manage multiple supplier interfaces for highly interdependent functions. It also creates switching costs for end-users who value validated subsystem performance.
-
Application-specific material and process leadership. Some firms emphasize high-rigidity ceramic cores for advanced semiconductor packages, while others prioritize dielectric formulations for high-reliability RF front-end modules, antennas, and power electronics. Specialized producers focus on automotive sensors, industrial electronics, or high-frequency and power applications, building reputations around reproducible performance in targeted domains.
-
Certification and reliability as market access tools. Companies serving automotive, aerospace, and defense applications treat quality certification as a core competitive asset. Adherence to established standards is not merely a compliance activity; it is a gating factor for program participation. Firms that have institutionalized these systems can secure long-cycle contracts that smaller, less certified rivals cannot easily enter.
HTCC Ceramic Substrates Market -
Regional specialization and proximity advantages. European and U.S.-based producers often compete by offering tailored custom substrates, turnkey fabrication up to high layer counts, and close collaboration with customers in defense, medical, and high-reliability industrial sectors. Chinese and Taiwanese manufacturers participate in the consumer and telecom supply chains, leveraging scale and proximity to volume-driven programs.
Recent corporate activity reinforces these strategies. The April 2026 commercialization of a high-rigidity multilayer ceramic core substrate for advanced AI semiconductors illustrates how incumbents are extending their technology into next-generation packaging requirements. The July 2025 capacity expansion for multilayer ceramic capacitors tied to LTCC performance, and the May 2025 launch of a substrate optimized for 5G and automotive radar, both demonstrate a pattern of synchronized product and capacity moves aimed at capturing demand in high-growth connectivity and mobility segments.
Looking forward, the market structure is likely to evolve along three lines. First, consolidation pressure will persist among smaller players who lack the scale or certification depth to compete across multiple applications, potentially leading to selective acquisitions or capacity partnerships. Second, differentiation will increasingly hinge on architectural innovation—layer count, via precision, thermal-mechanical performance, and embedded component integration—rather than on basic substrate supply. Third, new entrants and regional specialists may find opportunities in high-mix, lower-volume niches, especially where proximity, customization speed, or domain-specific expertise outweighs the advantages of the largest incumbents. The overall trajectory suggests a market that is consolidating at the top while remaining open to specialized value creation below the leading tier.
Future Trends and Commercial Implications (2026–2032)
Expansion into Advanced Packaging and AI-Enabled Semiconductor Systems
One of the most significant trends is the extension of LTCC substrates into advanced packaging domains associated with AI and high-performance computing. The commercialization of high-rigidity ceramic core substrates with circuit miniaturization indicates that LTCC is being evaluated for structural and interconnect roles beyond conventional RF modules. As semiconductor architectures continue to push thermal and dimensional requirements, LTCC's combination of stability and integration density can create opportunities in packages that demand precise alignment, mechanical robustness, and embedded functionality. For suppliers, this is a route to higher value-add and longer program lifecycles; for end-users, it may offer a pathway to consolidate interconnect functions and reduce packaging complexity.
Continued Growth in Automotive and High-Frequency Connectivity Applications
Automotive electronics and high-frequency connectivity are expected to remain central growth engines. The expansion of radar-based sensing, 5G-related RF modules, and power electronics in vehicles supports steady demand for substrates with consistent RF behavior and strong reliability credentials. At the same time, consumer electronics will continue to provide volume, though margin profiles may differ. The commercial implication is that suppliers must be able to straddle both high-volume cost sensitivity and high-reliability performance requirements without compromising quality. Companies that can manage these dual demands with disciplined process control and application-specific engineering will be better positioned to capture share.
Stabilization of Input Conditions Likely to Shift Competition Toward Process and Integration Capability
With alumina feedstock prices stable, no reported force majeure events in the supply chain, and no new tariffs or export controls targeting LTCC materials, the immediate cost environment is unlikely to be a differentiating shock factor. This shifts the source of advantage toward manufacturing precision, yield management, material formulation, and integration capability. Firms that can deliver higher performance per layer, reduce defect rates, and offer validated subsystem-level solutions will capture more value than those competing primarily on price. For procurement teams, this means that supplier selection should weigh process maturity and qualification depth as heavily as unit economics.
Potential Risks and Uncertainties
Several uncertainties warrant attention. First, while the input environment has been calm, any future disruption in alumina availability or precursor logistics could quickly alter cost dynamics and lead-time reliability, particularly for high-volume programs. Second, the trajectory of automotive and telecom demand is subject to broader macroeconomic and cycle risks; a slowdown in vehicle production or a shift in telecom capex could temporarily soften demand in specific segments. Third, as LTCC substrates extend into advanced packaging and higher-performance domains, qualification and technical validation requirements may intensify, increasing time-to-revenue and raising the cost of failure. Firms should plan for scenario variability in both demand and validation timelines.
Strategic Actions for Decision-Makers
For Manufacturers and Substrate Suppliers
-
Invest in differentiated architectural capabilities. Prioritize improvements that raise performance without sacrificing yield, such as advanced dielectric control, via precision, layer integration, and thermal-mechanical robustness. Product launches paired with targeted capacity expansion, as seen in recent 5G and automotive radar moves, are more effective than undifferentiated volume increases.
-
Deepen application-specific qualification and documentation. Strengthen ISO 9001 and AEC-Q200-aligned processes where relevant, and build evidence packages that support automotive, aerospace, and defense participation. Reliable certification infrastructure is a market-access advantage in high-reliability segments.
-
Align capacity with high-growth demand clusters. Use demand signals from consumer, automotive, and connectivity segments to calibrate expansions. Synchronizing substrate capacity with complementary component availability can improve system-level value and reduce customer integration friction.
For Investors and Strategic Partners
-
Focus on firms with material and process differentiation rather than pure scale plays. In a stable input environment, the companies most likely to capture margin and share are those with proprietary ceramic formulations, high layer-count capability, and proven high-reliability qualification. Evaluate pipeline activity, such as advanced packaging substrate development, as an indicator of future value creation.
-
Monitor integration and geographic diversification. Track how leading players extend into adjacent component businesses and how regional specialists position around customization and proximity. Consolidation among smaller firms and selective partnerships may create opportunities for entry at favorable valuations or with strengthened capability sets.
For Procurement and Engineering Leaders
-
Prioritize supplier capability depth over headline price. In LTCC substrates, process consistency, qualification evidence, and integration support often determine long-term total cost more than initial unit price. Assess suppliers on yield stability, layer-count capability, RF and thermal performance consistency, and ability to support custom requirements.
-
Plan for multi-application supply strategies. Because demand spans consumer, automotive, and high-reliability segments, consider dual-sourcing or application-specific supplier assignments to balance volume needs with qualification requirements. Engage suppliers early in design cycles to align material and process choices with end-system performance goals.
The LTCC ceramic substrates market is entering a phase where growth is sustained, but the nature of competition is becoming more refined. Stable input conditions, predictable regulatory expectations, and a concentrated but still diversified supplier base create a setting in which process excellence, application-specific engineering, and integration capability will determine who captures durable advantage. The companies and organizations that prepare for these dynamics now—by investing in differentiated capabilities, strengthening qualification infrastructure, and aligning supply strategies with application realities—will be better positioned to convert market growth into commercial value through 2032 and beyond.
For teams seeking a deeper, segment-specific view of regional demand distribution, application splits, type-based revenue patterns, concentration benchmarks, and detailed company profiles, a comprehensive research report provides the structured data and tailored scenarios needed to support precise planning. Detailed breakdowns and customized recommendations can help translate these strategic trends into concrete operating decisions.
For detailed analysis of this topic, please visit the official page: LTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com